Your EA does not know what a perpetual contract is. It reads a candle series, marks the last down candle before displacement, waits for price to trade back into it, and sends an order. Same rules, same stop, same target — whether the symbol behind the chart is spot BTC/USDT or the perpetual that tracks it.
The exchange knows the difference, and it enforces that difference on your position rather than on your strategy. One of those two markets can close the trade at a price you never chose, charge you rent every few hours for holding an idea that turns out to be right, and manufacture the exact wick shape your liquidity logic was built to hunt. The other can do none of those things.
So this is not a page about what spot and perpetual are. It is about the four things that change inside an already-working automated setup when you flip the market-type switch — and the one configuration decision that follows from them. The rest of the playbook for running ICT across crypto and forex stays exactly where you left it.
Key Takeaways
A perpetual adds a second invalidation level the EA never placed: when leverage pulls the liquidation price inside the stop distance, the exchange ends the trade before the strategy can.
Leverage does not change the money at risk — size still comes from risk divided by stop distance. It changes the margin posted and where liquidation sits, so pick leverage from the stop distance, not the other way round.
Funding accrues on notional and on the clock, so a correct-but-slow perpetual hold can cost a meaningful slice of the planned risk while the same spot position costs nothing to carry.
Default to spot for multi-day holds, use a perpetual when you need exposure beyond your cash or a native short, and if you run both, count the exposure once.
Table of Contents (23 min read)Contents
The Same ICT Signal, Two Markets to Execute It On
An Expert Advisor (EA) running smart money concepts is market-type blind by construction. Market structure, the order block, the displacement leg, the stop below the block — none of that logic contains a variable for "am I holding the coin, or a contract about the coin". Point the same compiled EA at two charts and it will produce two identical trade tickets.
What differs is the container those tickets land in. Four things, in the order they matter to your risk:
What can end the trade. On spot, only your exit logic. On a perpetual, your exit logic or the liquidation price, whichever price gets there first.
What the position costs to open. Spot consumes the full notional. A perpetual consumes margin, which is a fraction of it — and that fraction is what creates a liquidation price in the first place.
What the position costs to hold. Spot: nothing, forever. Perpetual: a funding payment at every settlement window, in one direction or the other.
What the wicks mean. On spot, a spike beyond structure is participants trading. On a perpetual, it can also be the exchange force-closing other people's positions — a different animal that behaves differently afterwards.
There is a fifth, duller difference that trips up more EAs than any of the above: the two markets are two separate symbols. On MetaTrader 5 reached through a connector, a pair's spot market and its perpetual arrive as distinct instruments with distinct contract specifications — different tick size, different minimum volume, sometimes a different quote convention. Get the symbol mapping wrong and the EA trades happily, even profitably, on the wrong market for weeks before anyone notices.
Mechanics Side by Side: Ownership, Leverage, Funding, Liquidation, Expiry
Here is the whole mechanical difference in one view, framed the way an automated system meets it rather than the way a spot buyer meets it.
Mechanics at a glance
What the EA is trading into
Spot market
Perpetual contract
What you actually hold
The coin itself, sitting in your exchange balance
A contract whose value tracks the coin's price
Leverage available
None by default — one unit of cash buys one unit of exposure
Selectable, and often far above 1x
Capital the position consumes
The full notional value, paid up front
Margin only — a fraction of the notional
Cost of simply holding
Nothing. A position can sit open indefinitely for free
Funding paid or received at every settlement window
Forced closure
None. Nobody can close the position but you
A liquidation price the exchange enforces on your margin
Expiry
Never — the coin stays yours
Never either — that is what makes it perpetual rather than a dated future
Going short
Needs borrowed coin, where the venue offers it at all
Native and symmetric to a long
What can end the trade
Only the EA's own exit logic
The EA's exit logic, or the liquidation price, whichever comes first
Eight mechanical differences, but only two of them rewrite the EA's risk: the running cost of holding, and the second thing that can close the trade.
Read the last two rows again, because they are the entire article. Everything above them is accounting. "Cost of simply holding" and "What can end the trade" are the two rows that reach into a running strategy and change its numbers without changing a single line of its logic.
Does the Liquidation Price Override the EA's Own Stop-Loss?
Yes — whenever it sits closer to entry than the stop does. And it does not override the stop so much as pre-empt it: the stop is never cancelled, it simply never gets reached, because the position stops existing first.
The two levels are enforced by different parties for different reasons. Your stop-loss is an instruction you gave the venue about your strategy's invalidation point. The liquidation price is the venue's instruction about its own exposure — the price at which your posted margin no longer covers the position's loss. It exists whether or not you thought about it, it moves as your margin balance changes, and no EA setting can push it further away except by using less leverage or posting more margin.
Three properties of that level surprise people the first time:
It is usually evaluated against the mark price, not the last trade on your venue. Exchanges derive a mark price from an index of several spot venues precisely so that one thin book cannot liquidate everybody. The consequence cuts both ways: a violent wick on your own chart may not liquidate you if the index never went there, and the mark can reach your liquidation level on a candle whose visible low did not.
It drifts. Fees and funding payments come out of margin. Hold a perpetual long through several settlements while paying funding, and the liquidation price you calculated at entry has quietly crept toward you.
It does not respect your risk budget. A stop is sized to lose a planned amount. A liquidation costs the margin backing that position, which on an isolated position is all of it.
Illustrative setup
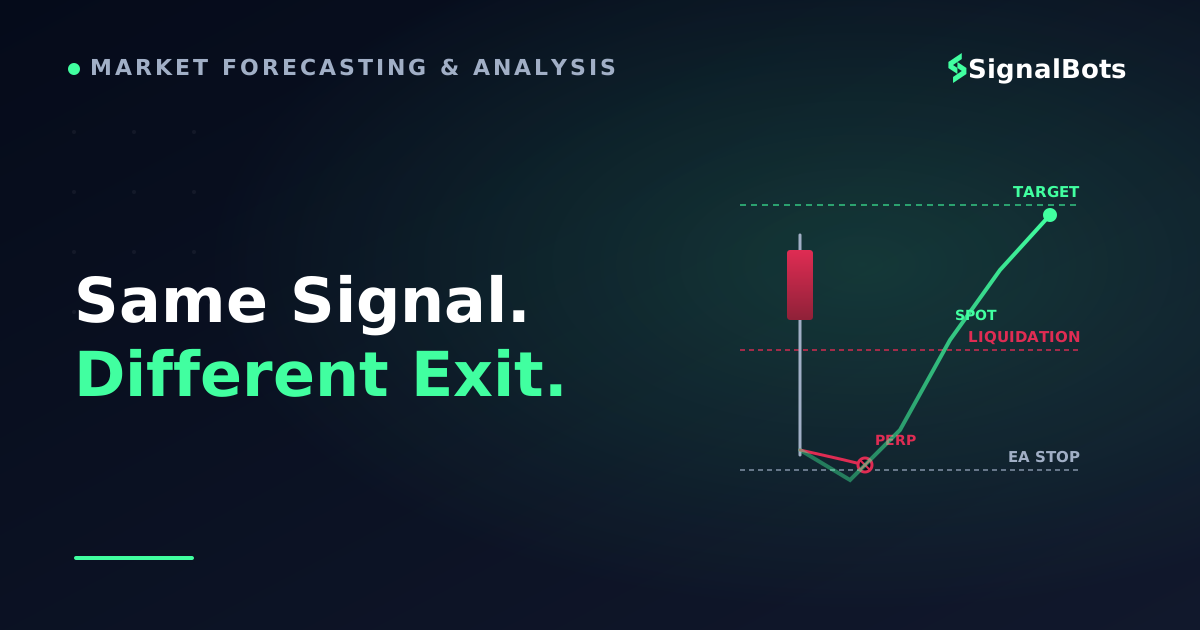
An order-block long where the liquidation price sits inside the stopBTC/USDT4H
Illustrative prices. The stop was never touched — the liquidation line, sitting between entry and stop, was, so the exchange ended the trade before the strategy could.
That chart is the failure mode in one picture. The EA read the order block correctly, placed the stop below it correctly, and the target eventually filled — but at that leverage the exchange's line sat between entry and stop, so a wick the strategy was explicitly designed to survive ended the trade instead.
The fix is not a better stop. It is arithmetic: the liquidation price has to sit outside the stop distance, with room to spare. That is a sizing decision, which is the next section.
One more mechanic worth knowing before you leave this section. On some venues, in fast markets, a position can also be reduced by auto-deleveraging even when it was never in loss — the exchange unwinds profitable counterparties to close out bankrupt ones. It is uncommon and you cannot configure around it, but an EA that assumes its position is still open when it is not will keep managing a ghost. Have the strategy re-read actual position state instead of trusting its own memory of what it opened.
Position Sizing: How Leverage Changes the Risk Math Behind Every Entry
Here is the part most readers have backwards. Leverage does not change how much money is at risk on an ICT entry. Risk is position size multiplied by stop distance, and both of those come from the chart, not from the margin tab:
Account equity × risk per trade = the amount you are willing to lose.
That amount ÷ (entry - stop) = position size.
That is the same position sizing rule on spot and on a perpetual, and it produces the same answer on both. On a $5,000 account risking 1%, with an entry at 60,000 and a stop at 58,800, the position is 0.0417 BTC either way. Spot pays $2,500 for it. The perpetual posts margin instead — and how much margin you post is what sets the liquidation price.
So leverage changes exactly two things:
How much capital sits idle. Lower margin frees cash for other positions, which is a genuine advantage when one EA runs several pairs at once.
Where the liquidation line lands relative to your stop. This is the number to actually manage.
A workable rule: pick leverage from the stop distance, never the other way around. If you want the liquidation to sit at least three stop distances from entry, the ceiling is roughly one divided by three times the stop percentage. A 2% stop caps you near 16x; a 1% scalping stop caps you near 33x; a 4% swing stop caps you near 8x. Notice the direction — the wider and more structurally honest your ICT stop, the less leverage you can carry, which is the reverse of the instinct that says a big stop needs a big multiplier to be worth taking.
Run your own numbers
Stop distance vs liquidation distance
Size from risk and stop distance, then check where leverage puts the liquidation line. A buffer under 1x means the exchange closes the trade before your stop does.
Account equity
$
Risk per trade
Entry price
$
Stop price
$
Leverage
Position size
—
Margin posted
—
Approx. liquidation
—
Liquidation buffer
—
Position size never moves when you change leverage — only the margin posted and the distance to liquidation do.
The liquidation estimate above is deliberately simple: it assumes an isolated position holding only its initial margin, and it ignores maintenance-margin tiers, which pull real liquidations slightly closer than the arithmetic suggests. Before committing to a leverage setting, check the exact figure with the crypto liquidation price calculator using your venue's own tiers — and remember the number is measured against equity, not balance, so an open loser elsewhere in the account moves it.
Funding: The Running Cost (or Income) Spot Doesn't Have
A perpetual never expires, so something has to keep it tethered to spot. That something is the funding payment: at fixed settlement windows, one side of the market pays the other. When the contract trades above the index, longs pay shorts; when it trades below, shorts get paid. It is not a fee the exchange collects — it is a transfer between traders, and it is the closest crypto analogue to the swap or rollover fee your forex EA already lives with.
Two details decide how much this matters to an automated ICT strategy:
It is charged on notional, not on margin. This is the trap high leverage sets. A position holding $33 of margin against $2,500 of exposure pays funding on the $2,500. Leverage shrinks the capital committed and leaves the carry untouched.
It accrues on the clock, not on the chart. A setup that is right but slow pays for every settlement it spends being right. Your stop never moved, your target never moved, and the trade got more expensive anyway.
Suppose a $2,500 perpetual long sits open for six days across three settlements a day. In a calm regime at 0.01% per settlement, the carry is small change. In a stressed regime at 0.10% — the kind that shows up when everyone is crowded onto the same side — the same six days look very different:
Illustrative carry
Illustrative: three settlements a day at 0.01% and at 0.10% of notional. On a trade risking $50, the stressed path costs almost as much as the stop itself — and the EA never sees it.
On a trade risking $50, the stressed path costs nearly as much as the stop itself. That is the number to keep in your head: funding is not a rounding error against a well-sized ICT risk budget, it is comparable to it. And the EA has no idea. Funding hits the margin balance rather than the position's floating profit, so a strategy that only reads open-trade profit will report a winner while the account books a scratch. To see what a specific hold does to a real position's net result, run it through the crypto futures P&L calculator with the carry included.
The mirror image is worth planning for too. When funding is positive and your ICT read is short, the market pays you to hold the position. A short entered from a bearish order block during an over-leveraged squeeze is subsidised for as long as the crowd stays wrong — the one case where a perpetual is strictly cheaper to hold than spot.
Liquidity Pools and Stop Hunts: The Second Source of Wicks
ICT teaches your EA to find resting orders: the stops parked just beyond equal highs, equal lows and obvious structure. That read is still correct on a perpetual. It is simply no longer the only thing living out there.
Beyond the same structural levels sits a second, mechanically different pool of liquidity — the liquidation prices of leveraged positions, clustered exactly where leveraged traders enter, which is exactly where structure is obvious. When price reaches them, the exchange itself becomes a forced seller or buyer with no price sensitivity at all. So on a perpetual chart a spike past an equal-lows cluster has two possible authors, and the same shape means two different things:
A liquidity sweep — someone deliberately reaching for resting orders, usually followed by a decisive reclaim of the level and a structure shift in the opposite direction.
A liquidation cascade — forced closing feeding on itself, which tends to accelerate through levels rather than reverse at them, and which often prints deeper on the perpetual than on spot.
One practical adjustment covers most of it: validate the wick against a second series. If the perpetual printed a spike the spot or index series did not, the move was a margin event on one venue rather than a market event — and treating it as a swept liquidity pool is how a strategy ends up entering into the middle of a cascade. The same discipline stops a perpetual-only wick from invalidating a setup spot never invalidated. The full mechanics of liquidity sweeps around funding-driven stop hunts deserve their own treatment; what matters here is only that a perpetual adds an extra source of them and spot does not.
A sweep and a cascade can leave the same shadow on the chart — what separates them is what happens next.
Worth noting how this cuts the other way: because spot has no liquidation engine, the same structural level tends to produce a shallower wick there. Slightly fewer false triggers, and slightly more setups that miss their entry by a few dollars. Neither market is cleaner — they are differently noisy, and a volatility filter tuned on one will be mistuned on the other.
A Worked Example: The Same Order Block, Traded Spot and Perpetual
To make the divergence concrete, here is one entirely hypothetical trade — no backtest, no live record, just the arithmetic of the sections above running end to end.
The setup: a $5,000 account, 1% risk, a bullish order block on BTC/USDT with entry at 60,000, an ICT stop at 58,800 below the block, and a take-profit at 63,600 for a 3:1 reward-to-risk ratio. Risk budget: $50. Position size: 0.0417 BTC. Price returns into the block, wicks to 59,120, then runs to the target over the following days.
Illustrative example
The same order block, two market types
Spot BTC/USDT
Buys 0.0417 BTC outright, tying up $2,500 of the $5,000 account
Only the EA's stop at 58,800 can end the trade early
The 59,120 wick is noise — the position survives it
Six days of holding cost nothing to carry
Target fills: +$150 on $50 risked, a clean 3R
Same signal, same $50 at risk, one single invalidation level.
VS
BTC/USDT perpetual at 75x
Same 0.0417 BTC of exposure for roughly $33 of posted margin
Liquidation lands near 59,200 — inside the 58,800 stop
The 59,120 wick closes the position at a full loss
Funding accrues at every settlement the trade stays open
Target still fills at 63,600, with the account no longer in it
Leverage moved the invalidation from your stop to the exchange's.
Illustrative example. Nothing about the ICT read changed — only which price level got to end the trade first.
The spot leg and the perpetual leg received the identical signal, at the identical price, with the identical stop. The signal was correct. One of them collected the 3R and one of them did not, and the reason had nothing to do with market structure.
Now change one input. Run the same perpetual trade at 10x instead of 75x and the liquidation sits near 54,000, far outside the stop — the 59,120 wick becomes survivable, the trade collects the same 3R as spot, and it does so while tying up $250 of margin instead of $2,500 of cash. The perpetual is not the worse instrument here. The over-leveraged perpetual is. The leverage dial is the whole difference between those two outcomes, and it is the setting most EAs leave at whatever the exchange defaulted it to.
Choosing Spot, Perpetual, or Both for Your ICT EA
The decision comes down to two questions, and neither is about which market is "better".
The decision rule
Should this EA instance run spot or perpetual?
Take itProceed with careSkip / stand aside
Two questions decide it: how long the setup stays open, and whether the carry over that hold is small next to the planned reward.
The honest summary of that tree: spot is the default for anything held across days, a perpetual earns its place when you need exposure your cash cannot cover or a native short, and leverage is a buffer setting rather than a size setting.
Running both at once is a legitimate third answer, and it is where most serious setups end up: spot for the swing timeframe, a perpetual instance for the intraday one. Two rules keep that from turning into an accident. First, give each instance its own magic number so the two copies never touch each other's positions. Second, count the exposure once — a spot long and a perpetual long on the same pair are one directional bet with two tickets, and risking 1% on each is really risking 2% on the same idea.
Before either instance goes live, the settings below are the ones that differ by market type. Every item on this list fails quietly rather than throwing an error, which is why it is worth ticking off deliberately.
Configuration checklist
Before you point the EA at a market type
0 / 10
Set the EA's symbol to the exact market-type ticker the exchange uses — a spot pair and its perpetual are two different symbols with different contract specifications.
Cap leverage so the liquidation price sits at least three stop distances from entry on your widest normal stop, not your tightest.
Size from risk and stop distance only. Leverage changes the margin posted, never the money at risk.
Confirm the position mode: on a netting account a second signal on the same symbol modifies the open position instead of opening a new one.
Give each market-type instance its own magic number so the spot and perpetual copies never manage each other's trades.
Set a funding threshold that blocks new perpetual entries, and decide in advance whether open positions ride or exit when the rate spikes.
Add a maximum hold time for perpetual positions so a stalled setup stops paying carry indefinitely.
Validate a suspicious wick against the spot or index series before letting a perpetual-only spike trigger or invalidate an entry.
Forward-test on the exact market type you intend to trade — the spot and perpetual series for the same pair are not identical.
Check that the kill switch closes positions on both market types, not only on the one you tested.
★
Checklist complete — you’re cleared to proceed.
Ten settings that differ by market type. Every one of them fails silently if you get it wrong.
Two of those deserve a sentence of their own. Position mode matters because a netting account merges a second signal into the existing position rather than opening a parallel one — the same EA that runs three concurrent setups on a hedging account will run one averaged position on a netting one. And forward testing on the actual market type matters because the spot and perpetual series for one pair genuinely differ: the perpetual carries its own basis, its own wicks, and its own behaviour around settlement times.
Pointing the EA at the Market Type You Chose
Once the decision is made, it turns into a plumbing question: your strategy lives in MT5 and the market you picked lives on a crypto exchange. Our crypto MT4/MT5 connector is the layer that closes that gap — it links an EA's order execution to spot and perpetual markets on the supported exchanges, so the same compiled strategy can be pointed at either one by changing the symbol it trades.
In practice the decision you just made shows up as a symbol on a chart. A pair's spot market and its perpetual appear as two separate instruments through the MT4/MT5 connector, each with its own contract specification, and the EA attaches to whichever one you chose. Running both means two charts and two instances — exactly the setup the magic-number rule above exists to protect.
To be clear about what it does not do: the connector routes and executes orders. It does not decide spot or perpetual for you, it does not cap your leverage, and it does not manage funding exposure or your liquidation buffer. Those stay your configuration, informed by the arithmetic on this page rather than by the plumbing underneath it. If the market-type question is still open, wire nothing yet — the decision tree above is the prerequisite, not this section, and which exchange you run the bot on is the decision after it.
Key Takeaways: Spot or Perpetual
Your EA will send an identical order to either market. Everything that diverges after that is the venue's rules acting on your position: a second invalidation level you did not place, a carry cost that accrues on the clock, and a class of wick that exists only because other people are leveraged.
Which means the market-type switch is not really a strategy decision. The ICT read is the same, the stop is in the same place, the target is the same distance away. What you are choosing is whether the exchange gets a vote on when the trade ends — and if you decide it does, how far away you are willing to let that vote sit.
FAQ
What happens to the EA's pending orders when a position gets liquidated?
The position closes, but the EA's mental model of it does not update on its own. Depending on the venue and the connector, an attached stop or take-profit can be left orphaned, and the EA may keep managing — trailing, partial-closing, timing out — a position that no longer exists. Worse, it may decline the next valid signal because it believes it is already in the market. Have the strategy re-read live position state from the account each cycle rather than trusting the ticket it remembers opening, and log a hard alert whenever remembered state and actual state disagree.
Is funding charged on my margin or on the full position size?
On the notional value of the position, not on the margin you posted. That is why funding bites hardest at exactly the leverage where it looks cheapest: the capital committed shrinks with leverage while the carry does not move at all. When you compare the cost of holding across leverage settings, compare it against the risk budget for that trade, not against the margin sitting behind it.
Do I need to change the ICT logic itself when I switch to perpetuals?
The entry logic, no — order blocks, structure breaks and displacement read the same on both series. The filters, yes. A perpetual chart carries wicks that spot does not, so a volatility or wick-rejection filter tuned on the spot series will fire differently on the perpetual. Add the market-type layer on top instead of rewriting the core: a leverage cap, a funding threshold, a maximum hold time, and a cross-check of suspicious wicks against the spot or index series.
Is spot always the safer choice for an automated strategy?
Safer in one specific and important sense: nothing but your own exit logic can close the trade, and holding costs nothing. It is not without risk, though — the position can still lose the full planned amount at the stop, and an unleveraged long in a falling market loses value exactly as fast as the price does. Spot removes liquidation risk and carry risk. It does not remove market risk, and it caps exposure at the cash you actually hold.
Can one EA run spot and perpetual instances at the same time?
Yes, and it is a common setup — but treat them as two deployments, not one. Separate symbols, separate magic numbers, separate leverage and hold-time settings, and a combined exposure limit that counts a spot long and a perpetual long on the same pair as a single directional bet. Anything less and the two instances will eventually double your intended risk on the same idea and call it diversification.
Why did my perpetual position close when the chart's low never reached my stop?
Almost certainly a liquidation triggered on the mark price rather than on the last traded price on your chart. Exchanges derive the mark from an index of several venues so that one thin order book cannot liquidate the whole market, which means the level that closed you was not the level you were watching. Two follow-ups: confirm the liquidation in the account's own history rather than inferring it from the chart, and recompute where your liquidation price actually sat after funding and fees had been drawn out of margin — it is usually closer than it was at entry.
Sources & Further Reading
Want to go deeper? These independent, authoritative sources shaped this guide — each one is worth reading in full:
The Crypto Desk is the SignalBots editorial team behind our digital-asset coverage. We research and write the guides and explainers on spot and perpetuals, exchange mechanics, funding rates and the 24/7 structure that sets crypto apart from every other market.

Discussions 0
Leave a comment