Nothing about the strategy changes when the account goes live. Same kill zones, same sweep, same shift in structure, same entry back into the gap, same compiled expert advisor sitting on the same VPS. What changes is what an ordinary bad week costs.
That is the whole problem. On an evaluation, a bad week costs a fee you already treated as sunk. On a funded account, the same week can end a relationship that was going to pay you for years. The strategy did not get worse — the consequence of variance got much more expensive, and almost nobody re-derives their sizing when that happens.
So the sequence that got you through the evaluation quietly becomes the thing that kills the funded account: wide discretionary stops, a lot size chosen rather than calculated, targets set at ratios that look impressive in a screenshot, and no rule at all for what happens after the trade is filled. It works often enough to pass once. It does not survive a hundred trades measured against someone else's floor.
This page settles the arithmetic. Smart money risk management for funded accounts is not a mindset — it is five numbers the EA computes in order: where structure puts the stop, what that distance makes the position size, what percentage the current account phase justifies, what target the structure actually offers, and what happens to the position after entry. None of them is a judgement call at 2 a.m.
Key Takeaways
The stop is not a risk setting - it is the price at which the read was wrong. Structure fixes it (swept extreme plus a spread-and-range buffer), and the stop distance then fixes the position size, never the other way round.
Risk per trade is a property of what a loss costs, not of the strategy: highest during the challenge, lowest immediately after funding when there is no buffer above the floor, and scaled to the buffer once the account is proven.
Per-trade sizing is not per-session sizing. Correlated setups found in the same kill zone - pending orders included - share one exposure budget, or three tickets quietly become one 1.5% bet.
Take the reward-to-risk the structure offers and use the resulting R as a filter; do not set a target ratio and hunt for setups that fit it.
Table of Contents (26 min read)Contents
Why the funded account punishes the risk profile that passed the evaluation
An evaluation is a bounded bet. You pay a fixed fee, you either reach a profit target inside a drawdown envelope or you do not, and if you do not, the worst case is that you buy another one. Variance is not purely your enemy there — a fat, lucky week is exactly what gets you across the target, and the downside is capped at the price of the challenge.
A funded account inverts every term of that. There is no target you must reach by a deadline, so upside variance buys you very little. There is still a floor, and touching it destroys the account, the profit split, and every payout that account would have produced. The payoff is now asymmetric in the opposite direction: small, repeatable gains are the product, and one outsized loss is uninsurable.
That inversion is the whole reason your risk percentage should fall even though your edge did not change. Risk per trade is not a property of the strategy. It is a property of what a loss costs you. The same expert advisor, with identical entry logic, deserves a different fraction on the two accounts because the two accounts are priced differently.
There is a second, quieter reason. Passing an evaluation is a very small sample — often a few dozen trades in a favourable stretch. It tells you the EA can produce a good run. It tells you almost nothing about the shape of its bad run, and the bad run is the only thing the funded account's drawdown rules ever measure. Sizing off the result of the evaluation is sizing off the most flattering slice of data you will ever have.
The rest of this page is the risk framework that follows from those two facts. If you also need the surrounding sequence — firm selection, the evaluation phases, the rule mechanics in order — that belongs to the wider guide on passing a prop firm challenge with an ICT EA; here we go straight at the sizing.
Where does the stop actually go? Anchoring risk to structure, not a pip count
Start by deleting a habit: the stop is not a risk setting. It is the price at which your read of the market was wrong. Those are different objects, and confusing them is what makes stop loss placement using smart money concepts go sideways in an automated system.
An ICT entry hands you the invalidation for free. If the setup is a long taken after a sweep of a prior low, the trade's premise is that the low was raided to fill orders and price is now leaving. If price returns and trades decisively below that low, the premise is dead — not unlucky, dead. That price, not a round number of pips, is where the stop loss belongs.
Two failure modes follow from ignoring that, and they are not symmetrical:
A fixed stop that is tighter than the structure gets taken out by ordinary noise inside the setup you were right about. The trade then runs to target without you, which is the most expensive kind of correct.
A fixed stop that is wider than the structure leaves money risk on the table for nothing, and — combined with a fixed lot size — silently varies your real risk trade to trade by a factor of three or four.
The second one is what actually breaches accounts. A fixed lot size with a variable stop distance means the widest-stop trades carry the biggest money risk, and wide stops cluster: they show up on messy, news-adjacent, low-liquidity structure, which is precisely when losers arrive in runs. Your worst three trades and your three largest positions are the same three trades.
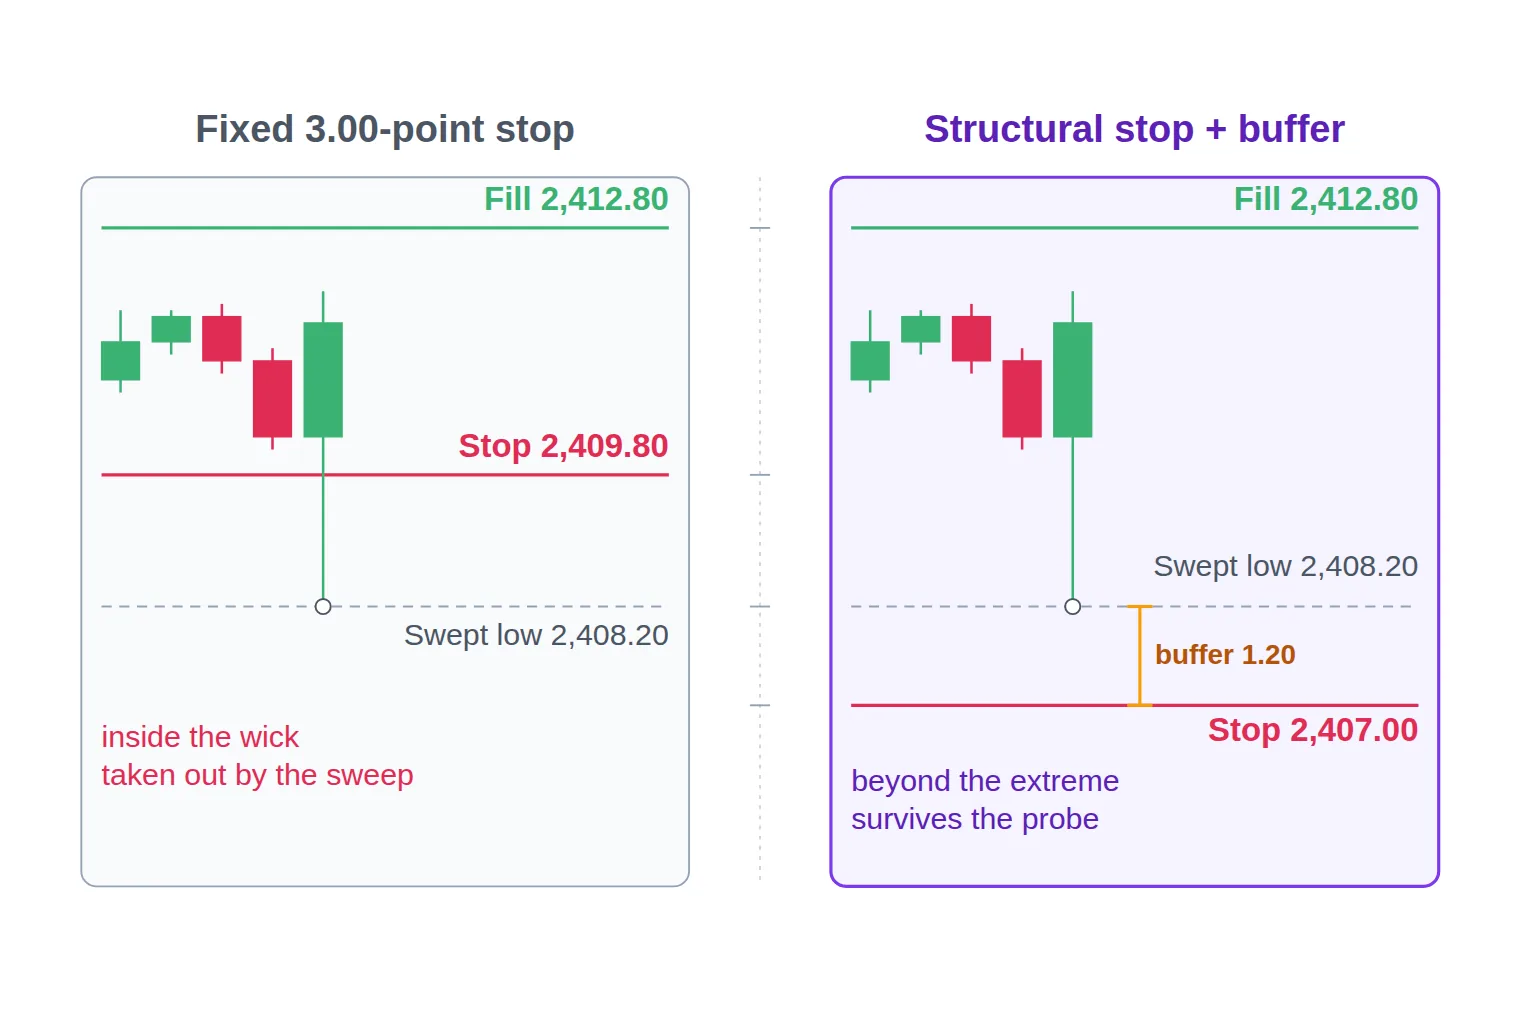
Put numbers on it. On the gold long we size later in this article, the fill is 2,412.80 and the low that was swept sits at 2,408.20. A stock "3.00-point stop" lands at 2,409.80 — above the swept low, inside the very wick that created the setup, so the next probe into that pocket takes you out of a trade whose premise is still perfectly intact. The structural stop goes to 2,407.00: beyond the extreme, plus a buffer.
Same setup, same fill: the fixed-pip stop is placed inside the liquidity pocket the entry depends on.
Reading the sweep wick and setting the buffer
The mechanical version, the one an EA can execute without interpretation:
Identify the candle that took liquidity — the one whose wick traded through the prior low (for a long) and closed back above it.
Take its extreme, not its body. The wick is the event.
Add a buffer beyond it. The stop goes past the extreme, never at it.
Measure the distance from your fill to that price, in the instrument's own points. That number, not a constant, is the input to everything below.
The buffer is the part most implementations get wrong, and it matters more than it looks. A stop resting exactly at the swept low is itself resting liquidity — it sits in the same pocket as every retail stop that just got taken, which makes it an attractive target for the next probe. Beyond that, the same candle prints a slightly different low on two different feeds, spreads widen at the exact moments these setups form, and your fill is not the mid price.
So derive the buffer from the instrument rather than from a preference. A workable rule: buffer = the current spread multiplied by two, plus a small fraction of the recent average candle range on the entry timeframe, floored at a fixed minimum in points. That scales with the symbol and with conditions, which a hard-coded "add 5 pips" does not — five pips is a wall on EUR/USD and a rounding error on a volatile metal.
Two disciplines complete the rule. First, account for slippage as a cost you will pay on the loss, not as something the buffer prevents: the buffer stops you being wicked out, it does not guarantee the fill price. Second — and this is the single edit that turns a controlled loss into a breach — the EA must never widen a stop after entry. Not on a retest, not on a "the setup is still valid" flag. If widening is in the code, delete the branch.
Turning stop distance into a position size
Now the causality runs one way and only one way: structure sets the stop, the stop sets the size. Every implementation that reverses that — pick a lot size, then find somewhere to put the stop — has already lost control of risk, because the only variable it can adjust to hit a money number is the one that encodes whether the trade idea is alive.
The position sizing rule itself is a single line of arithmetic.
whereStopDistance is the distance from your fill to the structural stop, measured in the instrument's own points — never a constant. PointValue is what one of those points is worth on one full lot. On a $100,000 account at 0.5%, a 5.80-point gold stop worth $100 per point per lot gives $500 ÷ $580 ≈ 0.86 lots.
The stop distance is an input, not an output — which is why the lot size changes on every trade even though the risk does not.
Position sizing for a funded trading account adds one wrinkle the retail version skips: the numerator is not always your balance. If your firm measures its maximum loss against the account's starting balance rather than your current equity, size against whichever of the two is smaller. Sizing 0.5% of a swollen balance while the floor is still pinned to the original number is how a good month funds a breach.
A worked example on a funded account
Take a $100,000 funded account, a 0.5% tier, and a gold long after a sweep of the Asian low.
Fill: 2,412.80. Swept low: 2,408.20. Buffer from the rule above: 1.20. Stop: 2,407.00.
Stop distance: 2,412.80 - 2,407.00 = 5.80 points.
Money at risk: $100,000 × 0.5% = $500.
One point on one lot of gold is worth $100, so one lot risks 5.80 × $100 = $580.
Size: $500 ÷ $580 = 0.862 lots, rounded down to the broker's 0.01 step → 0.86 lots, an actual risk of $498.80.
Three details in that example do real work:
Round down, never up. Rounding 0.862 up to 0.87 puts you over the tier. It is a rounding error on one trade and a systematic overshoot across a thousand.
If the computed size falls below the broker's minimum volume, the trade is not takeable. Do not size up to the minimum to "make it work" — a wide structural stop plus a minimum lot is the firm's floor arriving early. Skip the setup; it is the cheapest decision the EA will ever make.
Check the result against the firm's own lot cap before sending. Several firms limit volume per symbol or per account independently of your risk maths; the max lot calculator shows where that ceiling sits, and the EA should clamp to the lower of the two numbers rather than have the order rejected.
Run your own instrument and stop through the same chain here:
Structural stop to lot size
Enter the stop distance your structure produced — not a fixed pip count — and the value of one point on one lot for your symbol. The size to send is always rounded down to your broker's volume step.
Account balance (or the sizing base)
$
Risk per trade
Structural stop distance (points)
Value of 1 point on 1.00 lot
$
Broker volume step
Money at risk
—
Unrounded size
—
Size to send
—
Actual risk at that size
—
Change only the stop distance and watch the size move while the money at risk stays put — that is the whole behaviour you are trying to automate.
The same rule across accounts and instruments
The reason this cannot be a lookup table of lot sizes is visible the moment you tabulate it. Below, the risk percentage is constant, the account sizes are three common funded tiers, and the pip and point values are the conventional ones — 100 ounces per lot on gold, $10 per pip per lot on a major, $1 per index point per lot on a typical index CFD. Everything that moves, moves because structure moved.
Same risk, different sizes
Setup — instrument
Structural stop
$50,000 @ 0.5%
$100,000 @ 0.5%
$200,000 @ 0.5%
Tight sweep reversal — XAU/USD
5.80 points
0.43 lots
0.86 lots
1.72 lots
Wide sweep, same symbol — XAU/USD
14.20 points
0.17 lots
0.35 lots
0.70 lots
Gap fill entry — EUR/USD
17.5 pips
1.42 lots
2.85 lots
5.71 lots
Breaker retest — US30 CFD
85 index points
2.94 lots
5.88 lots
11.76 lots
Illustrative sizes at a constant 0.5% tier. Rows one and two are the same instrument on the same account — the size halves because the sweep was wider, and the money at risk never moves.
Rows one and two are the point of the table. Same symbol, same account, same percentage, and the position is less than half the size — because the market offered a wider invalidation that day. A fixed-lot EA would have taken both trades at the same volume and risked two and a half times more on the second one.
How much to risk per trade — challenge, newly funded, proven funded
With the mechanism settled, the remaining question is the percentage. Treat risk per trade as a function of what a loss costs at your current stage, and it resolves cleanly into three tiers.
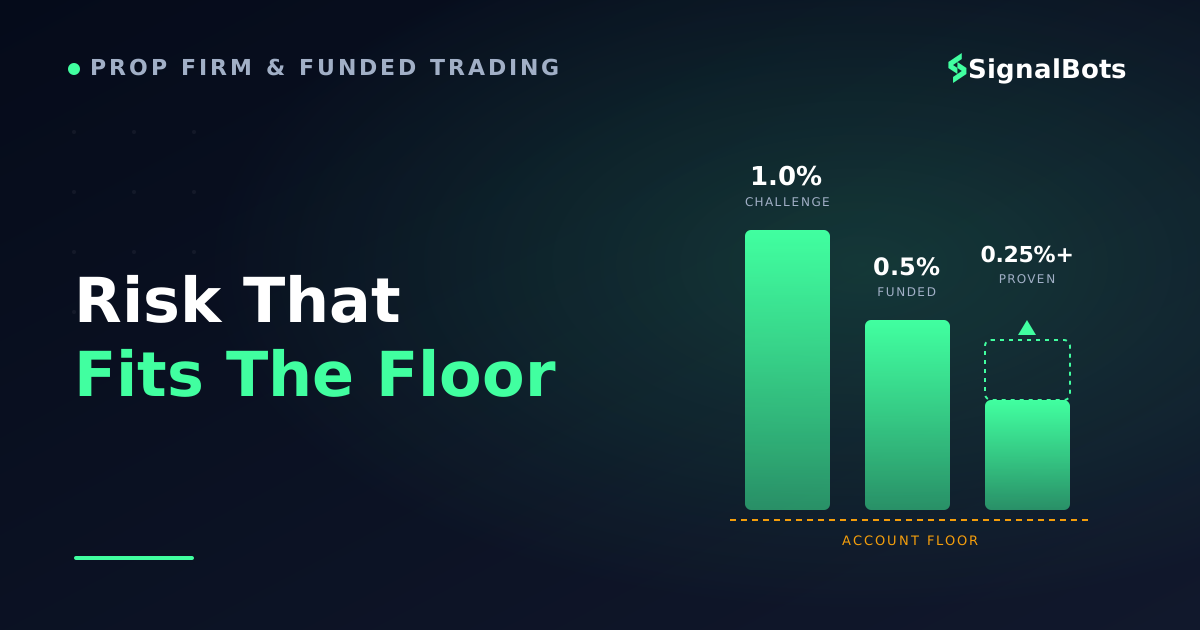
Challenge phase — a baseline near 0.5%, and 1% as a hard ceiling for your highest-conviction setup. This is the most aggressive you will ever justifiably be, and it is still not aggressive. The reason is not caution, it is arithmetic: a 5% daily floor absorbs ten losses at 0.5% but only five at 1%, and an ICT model that trades two kill zones can easily produce three or four losses in a session without anything being wrong. Sizing so that a normal bad day cannot end the attempt is worth more than reaching the target a week earlier.
Newly funded — cut it, typically to 0.25–0.5%. Two things changed at the moment you passed. The account now has option value: every future payout it produces is on the line, so the cost of a breach is no longer a fee. And your buffer is zero — you are sitting exactly at the starting balance, with the maximum-loss floor at its full distance and nothing banked above it. This is the single phase where traders most often keep their evaluation settings and most often lose the account.
Proven funded — risk scales with buffer, never with confidence. Once you hold real profit above the starting balance and have taken at least one payout, returning to the higher tier is defensible, but tie it to a number rather than a feeling: raise the tier only on the portion of the account that sits above the floor's reference point. When the buffer shrinks, the tier shrinks with it, automatically, in code.
Nothing upstream changes across the three phases - only the fraction the account is allowed to push through.
Two rules sit on top of the tiers and matter as much as the tiers themselves.
The two-stop rule. After two full stop-outs in one session, the EA stops trading for the day. This is not superstition about streaks — it is an information rule. Two consecutive losses on setups drawn from the same higher-timeframe premise usually mean the premise is wrong, and the third trade is not an independent sample of your edge, it is the same wrong idea at a worse price. Encoding it costs you a handful of good trades a year and removes the specific sequence that produces most breaches.
Halve the tier below the high-water mark. When the account is in maximum drawdown territory — say, more than a third of the way from the high-water mark toward the floor — cut the risk percentage in half until the account makes a new high. Sizing smaller while recovering feels like it slows recovery, and it does; it also makes recovery possible, because the loss you must claw back grows faster than the gain you need to claw it back with.
The constraint nobody sizes for: correlated setups in the same kill zone
Every rule so far is a per-trade guarantee. An automated system does not trade one at a time. An ICT EA scanning a basket during the London window will happily find a valid long on EUR/USD, a valid long on GBP/USD, and a valid short on USD/CHF from the same dollar-weakness read, and open all three at 0.5%.
That is not 0.5% risk. On the dollar leg it is close to 1.5% of a single idea, expressed three ways, and if the read is wrong all three stops are hit inside the same twenty minutes.
Where an EA's three positions are really one bet
6×6 matrix
Inverse
-1.0-0.50+0.5+1.0
Aligned
Illustrative relationships, not a live reading — the pattern is the point. Three long majors and a short USD/CHF are one dollar position wearing four tickets.
The fix is a second sizing layer that operates on groups rather than tickets:
Define exposure groups the EA can compute — USD-denominated majors, metals, equity indices, JPY crosses. A symbol belongs to exactly one.
Cap the group, not just the trade. Total open risk within one group should not exceed roughly one and a half times your single-trade tier; a second setup in a group already holding a full position gets sized down or skipped.
Cap the book. Total open risk across all groups stays inside a session budget you set deliberately — for most funded accounts, well under half the daily floor.
Count pending orders as open risk. This is the classic implementation bug: three limit orders resting inside the same gap look like zero exposure to a naive open-trade limit and become three full positions in one impulse candle.
None of this requires a correlation engine. A static group map, refreshed occasionally, catches the exposure that actually hurts.
What reward-to-risk ratio actually fits an ICT setup?
The ICT community's public reward-to-risk ratios are selection bias in numeric form. A 1:10 runner exists — it is the best trade of the month, screenshotted after the fact, and it is not the distribution you will trade. Building a funded account around targets that far away means most of your correct reads close at breakeven or reverse before they pay, and the account stalls while the drawdown clock keeps running.
Start from the relationship instead of from a preferred ratio. A strategy's break-even historical win rate is 1 ÷ (1 + R). At 2R you need better than one in three. At 5R you need better than one in six — which sounds comfortable until you notice what it implies about your losing sequences: at that hit rate, runs of six and seven losses are ordinary, and six losses at 0.5% is 3% of the account. On a 5% daily floor, the sequence merely has to land inside one session to end the account, and it does not care that the seventh trade would have paid for all of them.
Where the edge actually turns positive
Expected value per $100 risked — win rate × reward-to-risk
Hover a cell to see the expected value per $100 risked.
Hover any cell for its expected value. The break-even boundary — not the biggest number in the corner — is the line your configuration has to sit clear of.
Two readings of that grid matter for an ICT model specifically. First, the profitable region is wide: modest ratios at plausible hit rates clear break-even comfortably, which is why chasing the corner is unnecessary. Second, the cells are only meaningful if the win rate you plug in is the one your system produces at that ratio — and the win rate falls as the target moves away. R and win rate are not independent dials, and any backtested or historical figure you feed into it carries the caveats set out in our risk warning.
So invert the usual practice. Do not set a target ratio and hunt for setups that offer it. Take the target the structure offers, then use the resulting R as a filter.
The target is the next opposing liquidity pool, the fill of the higher-timeframe gap, or the equal highs the model is drawn toward — a place, not a multiple.
Measure the resulting R-multiple from your fill and your structural stop.
If it comes out below roughly 1.5R, do not take the trade and do not tighten the stop to manufacture the ratio. A setup whose invalidation is nearly as far as its objective is telling you the entry is late.
That single inversion fixes the reward to risk ratio for ICT setups without any argument about whether 1:3 or 1:5 is "correct". The market decides the ratio; your job is to decline the ones it prices badly. Track the realised distribution over enough trades and your expectancy becomes a measured number rather than an aspiration.
After entry: partial exits and the breakeven stop
A risk framework that stops at the entry is half a framework. The most common way a sound plan still bleeds a funded account is the round trip: a trade reaches 2R, gives it all back, and closes at the stop. The profit and loss statement records one ordinary loser. The equity curve records a swing that, on a firm measuring a trailing maximum loss against your peak equity, may have moved the floor up beneath you before it happened.
What the EA does between the fill and the final exit
1
Fill — full risk live
Position opened at the structural size. Stop at the wick plus buffer, both targets already mapped from the liquidity draw.
2
T1 — first opposing pool
Price reaches the nearest pool against the trade. Close a defined portion of the position, banking the partial.
3
Stop to entry plus costs
Move the stop to the fill price plus spread and commission, so a stop-out now returns a true zero rather than a small loss.
4
T2 — the higher-timeframe draw
Close the remainder at the objective the model was drawn to, or trail behind each new structural low once it is exceeded.
The sequence is event-driven, not time-driven: every transition is triggered by price reaching a level you identified before the fill.
Three points of precision separate this from the version that gets repeated everywhere:
Breakeven is not the entry price. Moving the stop to your fill leaves you paying the spread and commission on the exit. Move it to entry plus costs, or the supposedly protected portion of the trade still loses money every time it triggers — and it triggers often. The break-even stop should return an actual zero.
Trigger the move structurally, never on a timer or a fixed distance. "Move to breakeven at +15 pips" is the same mistake as a fixed stop, wearing different clothes. Tie it to the event: price reached the identified pool, or a displacement leg closed beyond it. If the structure that justified the entry has not yet produced anything, the trade has not earned protection.
Be honest that the partial costs you expectancy. Closing half at 1R on a trade destined for 2R caps that trade near 1.5R. You are buying variance reduction with return, deliberately. On your own account that trade may not be worth making. On a funded account — where the floor is external, the drawdown may trail, and survival is the product — it usually is. Size the partial take profit as a considered price, not as a reflex, and if you prefer to keep the full R, take the variance somewhere else instead. The same logic decides whether the remainder rides a fixed T2 or a trailing stop: a trail keeps the tail, at the cost of giving back part of the move on every trade that does not run.
Where this framework stops and the rule mechanics start
Everything above is the sizing backbone. It is deliberately silent on three adjacent mechanisms, each of which is its own build:
The daily loss limit. Sizing makes a breach unlikely; it does not enforce anything. Staying under the 5% daily drawdown line needs a latching kill-switch with its own reset logic — a control-flow problem rather than a sizing one. The prop-firm drawdown calculator shows how much headroom your configuration actually leaves.
The consistency rule. Several firms require that no single day dominates your total profit, which can be violated by a perfectly-sized system that simply had one excellent session. Check the shape of your distribution against the consistency-rule calculator before it becomes a payout problem.
Each of those is a different mechanism with a different failure mode. Build them separately; they all read their inputs from the numbers you have just fixed.
Putting it together
Risk management for an ICT expert advisor on a funded account reduces to one chain, evaluated in order, on every single trade:
Structure sets the stop — the swept extreme plus a buffer derived from spread and range.
The stop distance sets the size — balance × risk %, divided by distance × point value, rounded down.
The account phase sets the percentage — highest in the challenge, lowest immediately after funding, scaled to buffer once proven.
The exposure group caps the total — correlated setups share one budget, pendings included.
The liquidity draw sets the target — and an R below the filter is a trade you decline.
The pool sets the exit — partial at T1, stop to entry plus costs, remainder at T2 or trailed.
Every one of those is computable. That is the actual argument of this page: nothing in ICT risk management for prop firms requires discretion, and the parts people leave discretionary are exactly the parts that end funded accounts.
We started with
“the same EA, the same settings, and an ordinary bad week that costs a fee on one account and a career on the other”
and arrived at
five numbers derived in order, so the size changes on every trade and the risk never does.
The strategy did not change. The way its numbers are produced did.
A funded account does not reward a better read; it rewards a system whose worst sequence is survivable. Fix the chain — structural stop, derived size, phase-appropriate percentage, grouped exposure, structure-set target, event-driven management — and the rule-specific mechanisms become arithmetic you can check in advance instead of alarms you react to.
Should risk be a percentage of balance or of equity?
Use whichever is smaller at the moment of the calculation, and check what your firm's maximum-loss rule references. Sizing off equity while floating profit is open inflates every position on exactly the day your open trades are already winning; sizing off a balance that has grown well past a floor still anchored to the starting number understates how close you are to that floor. Taking the minimum of the two is one line of code and removes both errors.
What if the structural stop is so wide that the calculated lot size is below my broker's minimum?
Skip the trade. That is the correct output, not an edge case to work around. A minimum lot on a very wide stop means the smallest position you can open already risks more than your tier allows — you would be taking a trade at, say, double your intended risk because the structure happened to be messy that session. Wide-stop setups are also the lower-quality ones on average, so the filter costs less than it appears to.
Does risking half as much per trade make the profit target take twice as long?
In expectation, roughly yes — and that trade is usually correct on a funded account, where there is no deadline. It is a real cost during an evaluation, which does have one, and that is precisely why the challenge tier is the highest of the three. What halving the tier buys you is a much longer losing sequence before anything breaks, and evaluations are failed by sequences far more often than they are failed by slowness.
Can I use a fixed dollar risk instead of a percentage?
Yes, and on a funded account it has a real advantage: a fixed dollar amount does not grow as the account grows, so your exposure stays flat while your buffer builds. The drawback is that it does not shrink either, so it must be paired with an explicit rule that cuts the amount after a drawdown. Percentage sizing does that automatically; fixed-dollar sizing does it only if you write it.
After a payout, should I size from the new balance or the original one?
Size from whatever your firm's maximum-loss rule is anchored to, which after a withdrawal is frequently the reduced balance rather than the peak. A payout removes buffer, so the phase logic should step back toward the more conservative tier immediately after the withdrawal clears, and step forward again only once fresh profit has rebuilt the cushion above the floor.
Should the EA size differently for the London and New York kill zones?
Not by session as such — but the inputs already differ by session, and the formula picks that up automatically. Spreads and average ranges are wider around the New York open, which widens the buffer, which widens the stop distance, which shrinks the position. If you find yourself wanting an explicit per-session multiplier on top of that, what you probably want instead is a session budget: a cap on total risk deployed per window, which is an exposure rule rather than a sizing rule.
Sources & Further Reading
Want to go deeper? These independent, authoritative sources shaped this guide — each one is worth reading in full:
The Funded Desk is the SignalBots editorial team covering prop-firm challenges and funded-account trading. We research and write the guides on evaluation rules, drawdown limits, payout structures and the discipline funded trading demands.

Discussions 0
Leave a comment