You just finished a backtest, or you're staring at a trading bot's stats page, and there it is: Sharpe ratio: 1.3. Is that good? Should you trust it? And what is it actually measuring?
The Sharpe ratio answers one deceptively simple question — how much return did this strategy earn for the risk it took? This guide takes you from the plain-English meaning to the formula, a worked calculation you can copy, how to tell a good number from a worrying one, and — the part most explainers skip — when a high Sharpe ratio is a red flag rather than a green light.
Key Takeaways
The Sharpe ratio is return per unit of risk — a strategy's excess return divided by the volatility of its returns.
Compute it from a return series and annualize it (multiply a daily Sharpe by √252) so figures are comparable.
As a rough guide, above 1 is good and above 2 is strong — but a very high Sharpe on a short record is a red flag, not a green light.
It's one signal, not a verdict: read it alongside drawdown, sample length and out-of-sample results.
Table of Contents (12 min read)Contents
What Is the Sharpe Ratio?
The Sharpe ratio measures return per unit of risk. Two strategies can post the exact same profit, but if one earned it in a smooth, steady climb and the other lurched there through gut-wrenching swings, they are not equally good — and the Sharpe ratio is the number that says so.
It works by taking the return a strategy earned above a risk-free baseline (what your money would make sitting in cash or short-term government bills) and dividing it by how much its returns bounced around — its volatility. A higher ratio means more reward for each unit of risk. That framing is why it's the most common way traders express a risk-adjusted return: it refuses to praise a strategy for big gains without asking what it went through to get them.
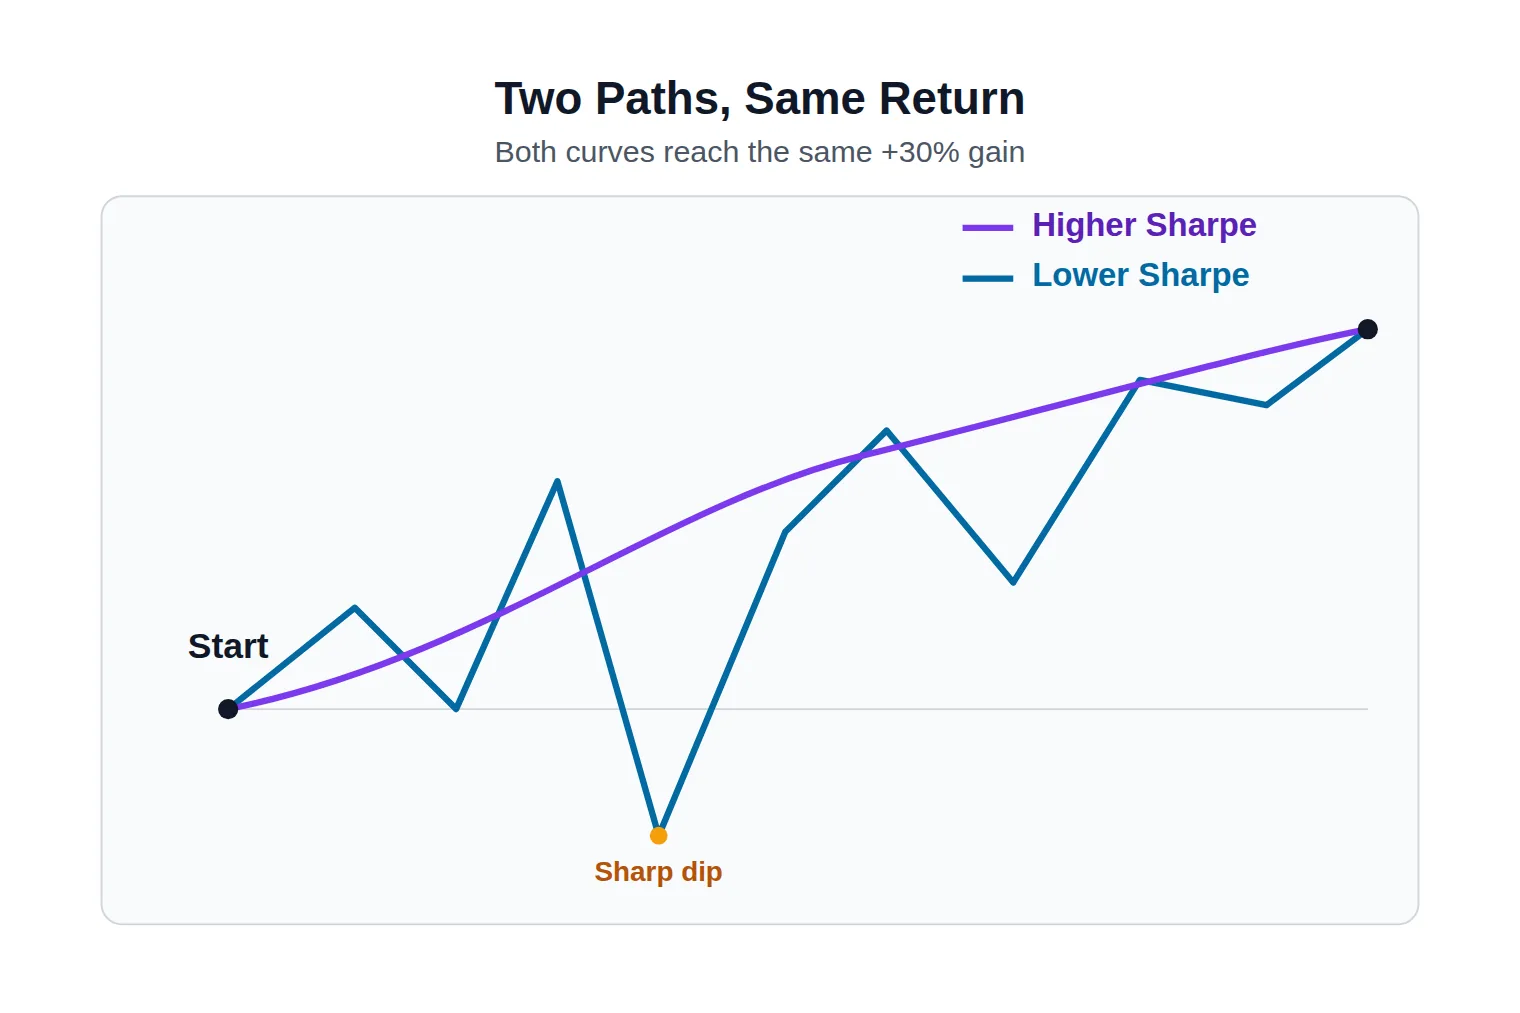
Picture two strategies that both end the year up by the same amount. One glides upward; the other gets there through deep dips and sharp rebounds. Same destination, very different ride — and a very different Sharpe ratio.
Two strategies, one return. The Sharpe ratio rewards the smoother path: the same gain, with far less stomach-churning risk.
The Sharpe Ratio Formula, Explained
Written out, the Sharpe ratio is compact:
Sharpe ratio — return per unit of riskfx
S = (Rp − Rf) ÷ σp
whereS = Sharpe ratio · Rp = the strategy's return · Rf = the risk-free rate (what cash or T-bills earn) · σp = the standard deviation of the strategy's returns, i.e. its volatility. Example: a 15% return, a 4% risk-free rate and 10% volatility give (15 − 4) ÷ 10 = 1.1.
Excess return on top, the volatility that produced it on the bottom.
Every term earns its place. The excess return (the numerator) is the reward that actually belongs to the strategy — subtracting the risk-free rate stops you from crediting it for gains you could have had risk-free. The standard deviation (the denominator) is the price of admission: the more a strategy's returns swing, the larger this number grows, and the harder the ratio penalizes it. Divide one by the other and you get reward measured in units of risk.
How to Calculate the Sharpe Ratio, Step by Step
You don't need special software — a column of returns and a spreadsheet will do. The process is four steps, and the one most guides gloss over is the last.
How to compute a strategy's Sharpe ratio
1
Gather the return series
Collect the strategy's periodic returns — daily, weekly, or monthly — across the whole backtest or live period.
2
Find the excess return
Subtract the risk-free rate from the average return. This is the reward left after what cash would have paid.
3
Divide by volatility
Divide that excess return by the standard deviation of the returns. The result is your per-period Sharpe ratio.
4
Annualize the result
Scale it to a year: multiply a daily Sharpe by √252 (≈ 15.9), or a monthly Sharpe by √12, so numbers compare.
Four steps — and the annualizing step is the one most guides skip.
That final step matters more than it looks. A Sharpe ratio computed from daily returns is not comparable to one computed from monthly returns unless you scale both to the same horizon. The convention is to annualize: because volatility grows with the square root of time, you multiply a daily Sharpe ratio by the square root of the number of trading days in a year — √252, or about 15.9. A monthly figure gets multiplied by √12. Skip this and a "daily Sharpe of 0.07" looks dreadful next to an annual 1.1, when they can be the very same strategy.
Here is the whole thing on one illustrative example. Suppose a strategy's backtest shows a 15% annual return with 10% annualized volatility, while risk-free bills pay 4%. The excess return is 15% - 4% = 11%, and dividing by the 10% volatility gives a Sharpe ratio of 1.1. Change the inputs to see how it moves:
Try the numbers
Sharpe ratio calculator
Plug in your strategy's annualized numbers and watch the ratio move. Push volatility up while holding return fixed to see the penalty.
Annual return (%)
Risk-free rate (%)
Annual volatility (%)
Sharpe ratio
—
Notice what the calculator makes obvious: push volatility up while holding return fixed and the ratio falls. That is the entire point of the metric.
What Is a Good Sharpe Ratio?
There is no universal pass mark, but there is a widely used rough guide. As a first read, use this:
Sharpe ratio
How to read it
Below 0
The strategy earned less than a risk-free parking spot — cash would have beaten it.
0 – 1
Weak to fair. The returns don't clearly pay you for the risk you carried.
1 – 2
Good. A solid risk-adjusted result for a retail strategy with a real track record.
2 – 3
Very good — but start asking exactly how it was measured, and over how long a period.
Above 3
Excellent on paper. On a short or self-reported record, treat it as a warning, not a trophy.
A rough reading guide — not a hard pass mark. Context and sample length shift every band.
Two caveats keep those bands honest. First, context sets the bar. A retail trader running a strategy on a genuine, months-long track record can reasonably treat a sustained Sharpe ratio above 1 (after costs) as a good result. Large institutions, working with far more data and tighter risk controls, often won't look twice at an annualized Sharpe below 1. The same number means different things depending on who produced it and how much history stands behind it.
Second, a higher Sharpe ratio is not automatically better once you climb past "very good." That is where the metric starts to mislead — which is the next section.
Where the Sharpe Ratio Can Mislead You
The Sharpe ratio is a genuinely useful number, but it has blind spots that a careless reader — or a motivated seller — can exploit.
It is backward-looking. The ratio is computed entirely from past returns, so it describes what a strategy did, never what it will do.
It treats good and bad volatility the same. Standard deviation counts an upside surprise exactly like a downside one, so a strategy that mostly jumps in your favor is penalized for that "volatility" just as if it were losing. This is the specific gap the Sortino ratio was built to close — it divides only by downside deviation. If a strategy of yours has rare losses but strong upward bursts and still scores only a middling Sharpe ratio, it isn't necessarily weak; the Sharpe ratio is simply counting its good swings against it.
A very high number can signal the opposite of skill. An unusually large Sharpe ratio — especially on a short window or a marketing page — is often a symptom of overfitting: a strategy tuned so tightly to one slice of history that it looks flawless there and falls apart everywhere else. Cherry-picking the best three months and publishing the Sharpe from that window produces the same illusion. The skeptical reflex is the correct one.
Quick check
Knowledge check
A vendor markets a trading bot with a backtested Sharpe ratio of 4.5 measured over three months. What's the right first reaction?
Why
Real edges rarely post an extreme Sharpe over a tiny sample. A sky-high figure on three months of self-reported data usually means the strategy was tuned to fit that exact period. Ask for a long, out-of-sample, after-costs record before you trust it.
Using the Sharpe Ratio to Judge a Strategy or Bot
So where does this leave you when you're actually vetting a strategy or a bot? Treat the Sharpe ratio as one signal, not a verdict. It's an excellent first filter — a quick way to reject something whose returns clearly don't justify their risk — but a poor place to stop.
Read it next to the things it can't see. How deep did the losses get along the way — the drawdown the ratio smooths over? How long is the record, and was it tested on data the strategy never saw during tuning? A bot advertising a 3.0 Sharpe ratio on three months of self-reported results tells you far less than a modest 1.2 backed by two years of out-of-sample history.
It also helps to understand where the Sharpe ratio fits inside a full backtest rather than reading it in isolation — it is one output among several that, taken together, tell you whether an edge is real. On its own, a single ratio is easy to game; alongside the loss profile, the sample length and the out-of-sample results, it becomes genuinely informative.
The Bottom Line
The Sharpe ratio earns its popularity: one number, honestly answering how much reward a strategy produced for the risk it carried. Compute it, annualize it, and read it against a rough scale — then remember its limits, and never let a single impressive figure do your thinking for you.
You opened with
“a Sharpe number on a backtest, unsure what it meant”
and now you can
read it, compute it, and know when to distrust it.
Read the number, then look past it
The Sharpe ratio compresses a whole return series into one honest question: how much reward did this strategy earn for the risk it took? That makes it a fast first filter — and a poor final verdict. Pair it with how deep the losses got and how the edge holds up out of sample, and you'll rarely be fooled by a pretty ratio again.
Continue your researchMaximum drawdown — the worst-case loss the Sharpe ratio hides→Profit factor — gross profit measured against gross loss→Expectancy — the average outcome you can expect per trade→
FAQ
Is a higher Sharpe ratio always better?
Up to a point. Moving from a negative or sub-1 ratio toward 1–2 genuinely reflects better risk-adjusted performance. But an unusually high ratio — say 3 or above on a short or self-reported record — more often signals overfitting or a cherry-picked period than a rare edge. Past "very good," get more cautious, not less.
What is the difference between the Sharpe ratio and the Sortino ratio?
The Sortino ratio is a close variant that divides return only by downside volatility, so — unlike the Sharpe ratio, which counts every swing — it doesn't penalize a strategy for its large upside moves.
What risk-free rate should I use?
Use the return on a short-term government instrument — a Treasury bill or its equivalent in your currency — matched loosely to your holding period. Many retail tools simply set the risk-free rate to zero, which slightly inflates the resulting ratio; that's acceptable for comparing your own strategies against each other, as long as you stay consistent.
Can the Sharpe ratio be negative?
Yes. A negative Sharpe ratio means the strategy earned less than the risk-free rate over the period — you would have done better leaving the money in cash. It's an immediate signal that the returns didn't compensate for the risk taken, or that the strategy simply lost money.
How much data do I need for a reliable Sharpe ratio?
More than most published figures rest on. A Sharpe ratio from a few weeks of returns is mostly noise — a handful of lucky trades can flatter it enormously. Favor figures built on long periods that span different market conditions, and give the most weight to results measured on out-of-sample data the strategy was never tuned on.
Sources & Further Reading
Want to go deeper? These independent, authoritative sources shaped this guide — each one is worth reading in full:
The Cross-Market Desk is the SignalBots editorial team for topics that span every market — platform connectors, copy trading, partnership and IB programs, and the general mechanics of trading automation. We research and write the guides that apply no matter what you trade.

Discussions 0
Leave a comment