You cleared the evaluation. The account is funded, the first profit is sitting in it, and your expert advisor is running the exact configuration that got you here. That configuration was tuned for a finish line — a target to reach before a limit stopped you. There is no finish line now. There is a balance that is partly yours, a floor somewhere below it, and a machine still optimising hard for a goal it already achieved.
The uncomfortable part is that the funded phase punishes the settings that passed the challenge. Aggression that was rational when the only cost of failure was a fee becomes the main threat to income once the account is producing it. And the moment a payout actually clears, the account is at its most fragile — the profit left, the floor mostly did not.
This is the decision layer that sits between "I passed" and "I keep getting paid": how much of the profit has to stay in the account, what trigger tells the EA to trade smaller, when to ask for the money, and how to trade the session after it lands. All four are arithmetic your EA already has the inputs for. None of them need a human watching a dashboard.
Key Takeaways
Size the cushion from your own numbers: daily-loss budget x worst losing streak + a gap reserve. On a hypothetical $100,000 account that requirement is larger than the drawdown allowance the firm hands you on day one, which is why the first payout is the risky one.
Tie the risk step-down to headroom, not to the profit target. Risk goes down when the account is thin, up while it is building the buffer, and down again once the surplus exceeds the payout you plan to request.
Under a trailing floor a withdrawal costs headroom dollar for dollar, because the floor stays anchored at your equity peak. Check which anchor your firm uses before deciding any withdrawal amount.
Recompute the mode before the first bar after a payout clears. The daily-loss counter resets overnight; the distance to the floor does not.
Table of Contents (22 min read)Contents
What Changes the Day Your EA Starts Trading Real Payouts
Three things change at once, and only one of them is obvious.
The obvious one is that money can now leave. A withdrawal moves cash out of the account permanently, which means the account can shrink for a reason that has nothing to do with trading.
The second is that the clock changed shape. During the evaluation the only counter that mattered was distance to target. In the funded phase the counter is the payout cycle — a window that opens, a request that gets processed, and a new cycle that starts. Your EA does not see that clock at all unless you give it to it.
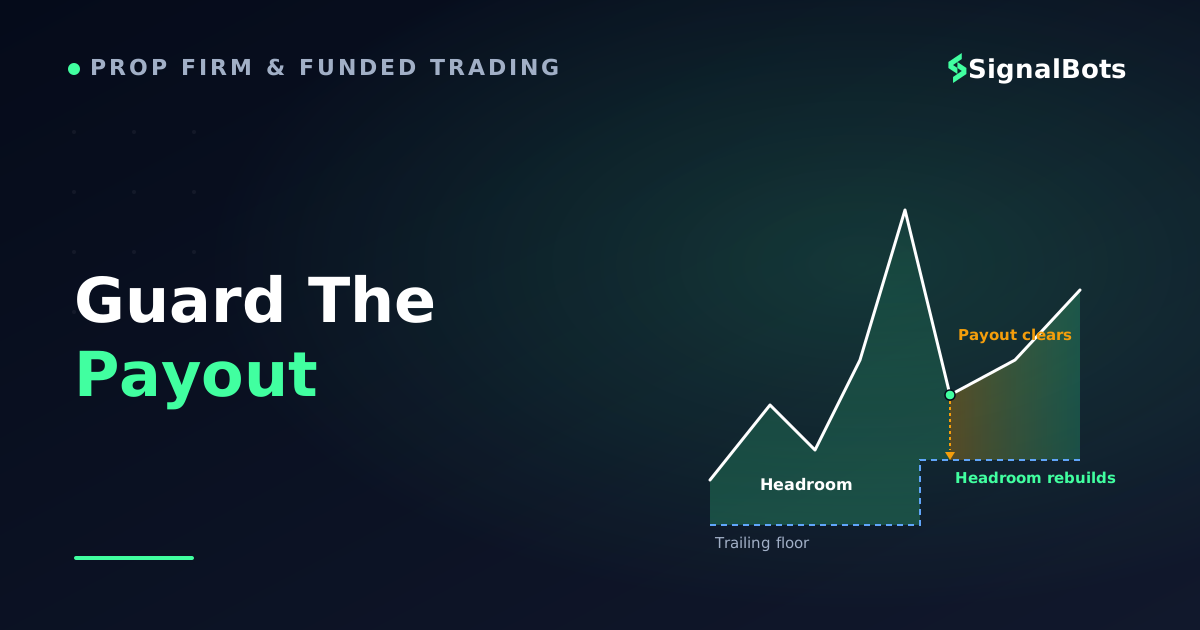
The third is the expensive one: a withdrawal reduces your equity, but it usually does not reduce the level at which the firm calls a breach. Whether it does depends entirely on how your firm anchors that floor, and this single fact decides every number in the rest of this article.
The funded loop
stateDiagram-v2
    state "Build - full configured risk" as Build
    state "Protect - risk stepped down" as Protect
    state "Payout pending - request submitted" as Pending
    state "Recovery - headroom below requirement" as Recovery
    state "Halted - loss guard fired" as Halted
    [*] --> Build
    Build --> Protect : surplus rises above required headroom
    Protect --> Build : surplus given back to the market
    Protect --> Pending : withdrawal requested at a flat moment
    Pending --> Recovery : payout clears and headroom drops
    Recovery --> Build : headroom rebuilt past the requirement
    Build --> Halted : daily or maximum loss guard fires
    Protect --> Halted : daily or maximum loss guard fires
    Recovery --> Halted : daily or maximum loss guard fires
    Halted --> Recovery : next session, guard re-armed
The transition most EAs never model is Pending to Recovery: the payout clears, headroom drops, and the machine is still sized for the mode it was in yesterday.
Notice that the loop has no exit. An evaluation is a path with an end; a funded account is a cycle that runs until something ends it. Most EAs are written for the path — one risk setting, one position cap, one daily budget, applied identically forever. The moment the account has money worth protecting, one setting is no longer enough, because the machine needs to behave differently depending on where in the cycle it currently sits.
There is also a vocabulary trap worth clearing early. Your firm measures the breach against equity, but pays you out of balance, and the two are different numbers whenever a position is open. If your EA reasons about balance rather than equity, every calculation below is measured against the wrong quantity at exactly the moments it matters most. A withdrawal and a losing streak draw down the same cushion — the account does not refill it for you.
How Big Should Your Payout Buffer Be?
"Build a buffer before you withdraw" is the standard advice and it is correct as far as it goes. It just stops one step short of being usable, because it never says how big — and the honest answer is that the size is not a preference, it is the output of numbers your EA already knows.
Start by naming what the buffer is for. It is not a cushion for feeling comfortable. It is a budget for a normal losing streak: the amount of equity that can disappear, in the ordinary course of the strategy doing what it does, without the account touching the floor. Every strategy has such a streak. Yours has a specific one, visible in your own forward test.
Does Retained Profit Actually Buy You Headroom?
Not always — and this is where most funded accounts get quietly hollowed out.
Firms anchor the breach floor in one of two ways. A static floor is fixed to the starting balance: your maximum drawdown allowance is subtracted once, at the beginning, and the level never moves. Under a static floor, every dollar of profit you leave in the account adds a dollar of distance to the floor. Retained profit buys headroom directly.
A trailing floor is anchored to the account's equity peak: the level rises behind you as the account makes new highs, and it never comes back down. Under a trailing floor, retained profit does not increase your distance to the floor at all — the floor follows it up. You are permanently allowed the same allowance, measured from wherever the account last peaked. Many firms stop the trailing once the floor reaches the starting balance, at which point profit starts buying headroom again; some do not stop it. Read your own rule text, because the difference decides whether the buffer strategy below is possible or impossible at your firm.
Now apply that to a withdrawal. Under a trailing floor, taking money out lowers your equity while the floor stays exactly where the last peak put it. The headroom lost equals the amount withdrawn, dollar for dollar. Nothing gives it back except new profit.
The Required-Headroom Formula
Required headroom - the cushion that never leaves the accountfx
Hmin = Ld × N + G
whereLd is the daily-loss budget your EA is allowed to spend, N the worst run of consecutive losing days your own forward test produced (rounded up by one), and G a reserve for gaps and slippage on a forced exit. On a hypothetical $100,000 account with a $5,000 daily budget, a worst run of three days and a $1,000 reserve, Hmin = $16,000.
Every number in this formula already exists inside your EA - none of it needs a dashboard.
Two of those three inputs deserve a comment.
The streak count is yours, not a convention. Take the worst run of consecutive losing days in your forward test, and add one — because the worst run you have observed is a sample, not a limit. If you have not run the strategy long enough to have a credible worst run, that is the finding: you do not yet know what to size the buffer against, and a conservative number is a placeholder rather than an answer.
The reserve is the cost of stopping, not the cost of trading. A forced exit during a gap or a thin session costs more than a clean stop. If you have already measured that on demo for your daily-loss guard, reuse the number; the underlying position-sizing rule does not change here, only the level it is measured against.
Every figure in this section is an illustrative arithmetic example rather than a projection of results — automated trading carries risk of loss, and our risk warning applies to all of it.
Example Buffers by Account Size
Take an account whose daily line is 5% and whose maximum drawdown allowance is 10%, with a worst streak of three days. Substitute your own firm's numbers where they differ — the shape of the answer does not change.
Account size
Daily-loss budget
Required headroom
Firm's starting allowance
Profit to retain before the first withdrawal
$25,000
$1,250
$4,000
$2,500
$1,500
$50,000
$2,500
$8,000
$5,000
$3,000
$100,000
$5,000
$16,000
$10,000
$6,000
Read the last two columns together, because that comparison is the whole point. The requirement is larger than what the firm hands you on day one. A freshly funded account does not have enough distance to the floor to absorb its own normal losing streak — which means the first withdrawal is not safe simply because a profit target was hit. It becomes safe once retained profit has closed the gap in the final column.
That also explains why the first payout is the dangerous one and the fifth is not. By the fifth cycle, a working strategy has usually banked the difference. On the first, it has not, and the payout that feels most deserved is the one taken out of the thinnest account you will ever run.
Safe-withdrawal calculator
Enter what your account looks like at a flat moment. The floor is the equity level at which your firm calls a breach - read it from your own rule set, not from your balance.
Current equity
$
Breach floor (equity level)
$
Daily-loss budget
$
Worst run of losing days
Gap and slippage reserve
$
Required headroom
—
Headroom you have now
—
Safe to withdraw now
—
A zero here is an answer, not an error - it means the account is still buying its own safety and has nothing spare to release.
The number that matters is the third one. Everything above it is bookkeeping; the featured figure is the only amount that can leave without pushing the account inside its own streak budget. If you want to model what the firm's split does to the cash that reaches you, the prop-firm payout split calculator handles that side separately.
Stepping the EA's Risk Down Once There's Something to Protect
The common version of this rule is "cut risk after you hit the profit target." It is directionally right and mechanically wrong, because the profit target is a milestone the EA passes once, while the thing you are protecting changes continuously.
Tie the step-down to headroom instead. Headroom is a live number, it moves with every trade and every withdrawal, and it is the quantity that actually determines whether the account survives. That gives three modes rather than a before-and-after.
Three modes, one input
EA setting
Recovery mode
Build mode
Protect mode
When it applies
Headroom below the requirement
Headroom covers the streak, no surplus
Surplus exceeds the payout you would request
Risk per trade
0.25x configured
1.0x configured
0.5x configured
Concurrent positions
1
Configured maximum
Configured maximum, minus one
Correlated exposure
One symbol per currency
Normal correlation cap
One symbol per currency
Setup filter
Highest-confluence entries only
Every qualifying entry
Every qualifying entry
Daily-loss budget
Half the usual budget
Full budget
Half the usual budget
What the mode is buying
Time to rebuild without breaching
The buffer itself
The payout already earned
Recovery and Protect look similar and mean opposite things: one is protecting an account that is thin, the other an account that is rich.
The counterintuitive row is the first one. Risk goes down at both ends and up in the middle — small when the account is thin because a streak would breach it, full when the account is doing the one job that fixes thinness, and reduced again once there is a payout's worth of surplus sitting there, because at that point the marginal trade is risking money you have already earned to chase money you have not.
Two implementation details decide whether this works or quietly does nothing.
The mode must be evaluated before sizing, on every bar, not once per session and not after an entry has been queued. An EA that computes its risk per trade first and consults the mode afterwards will size the trade in the mode it was in yesterday.
And the factors must apply to more than lot size. Halving the lot multiplier while leaving the maximum open trades limit untouched halves per-trade risk and leaves aggregate exposure exactly where it was — four half-size correlated positions are not a reduction.
If you want to sanity-check the ceiling a reduced mode implies before wiring it in, the prop-firm maximum lot size calculator works it out from the account limits.
Building the Step-Down Rule Into the EA's Logic
Here is the whole rule as logic rather than prose. It is deliberately platform-agnostic — every line maps to a value your EA can already read or already stores.
pseudocoderisk_mode_check
ON every new bar, BEFORE any entry or sizing decision:

    equity   = account equity          // equity, never balance
    floor    = breach_floor()          // static or trailing, per your firm
    headroom = equity - floor

    required = daily_budget * worst_streak + gap_reserve
    surplus  = headroom - required - planned_payout_request

    IF headroom < required THEN
        mode = RECOVERY
    ELSE IF surplus > 0 THEN
        mode = PROTECT
    ELSE
        mode = BUILD
    END IF

    risk_per_trade  = base_risk        * mode.risk_factor
    max_open_trades = base_max_trades  * mode.trade_factor
    daily_budget    = base_daily_limit * mode.budget_factor
    min_setup_grade = mode.setup_grade

FUNCTION breach_floor():
    IF floor_type == STATIC THEN
        RETURN starting_balance - max_drawdown_allowance
    ELSE                                  // trailing / high-water
        peak = MAX(peak, equity)          // peak never moves down
        RETURN peak - max_drawdown_allowance
    END IF
The mode is recomputed every bar, not once per payout - which is what makes it survive a restart, a weekend, and the day the withdrawal lands.
The breach_floor() function is the part worth writing carefully. Under a trailing anchor the peak has to persist across restarts, or a terminal crash on a Friday hands the EA a fresh, lower peak on Monday and it will happily calculate headroom it does not have. Store it the same way you store any other state that has to survive a restart.
One deliberate omission: there is no branch for "a payout is pending." That is on purpose. A pending request does not change the arithmetic — the money is still counted as headroom until it actually leaves, and the mode check picks up the change automatically on the first bar after it does.
Picking a Withdrawal Cadence That Doesn't Strip the Buffer
Once the amount is decided by formula, the only remaining question is when — and cadence is where an otherwise-sound buffer gets spent by accident.
Two failure modes cause almost all of it.
The first is requesting a withdrawal with positions open. Your floating P&L can move against you between the request and the moment it is processed, and depending on the firm the requested amount may already be deducted or ring-fenced. Equity falls from both directions at once. Request at a flat moment, and if your firm deducts at request time rather than at processing, pause new entries until it clears.
The second is sizing the request off the balance. A balance figure says what is in the account; it says nothing about the distance to the floor, which is the only quantity a withdrawal actually consumes. The request size should come out of the formula, every time, even when the balance looks generous.
That leaves the cadence itself.
Calendar cadence vs headroom-triggered cadence
Fixed calendar cadence
Requests a withdrawal on every payout window the firm offers
The request size is decided by the calendar, not by the account
Income is predictable, which makes it easy to plan around
A thin month still triggers a withdrawal that takes headroom with it
Needs no extra logic - the window is the whole rule
Predictable income, unpredictable headroom.
VS
Winner
Headroom-triggered cadence
Checks every window, but only requests when the surplus is positive
The request size falls out of the formula, not out of the calendar
Skips a window entirely when the account has nothing spare
Income is lumpy and occasionally zero for a cycle
Costs one arithmetic check before each window
Lumpy income, a floor you never walk toward.
The hybrid most funded traders end up with: check at every window, then request the smaller of what you wanted and what the formula allows.
The window decides when you look at the account; the arithmetic decides how much is allowed to leave.
Frequency has a second-order effect worth knowing. Frequent small withdrawals keep the account close to its floor more of the time but take the cash off the table steadily. Infrequent large ones let the buffer grow deep, then remove a large slice of it in one movement — which is precisely the situation the reset-day rule below exists for. Neither is wrong; the difference is where in the cycle the account spends most of its life, and only one of them ever leaves the account genuinely thin.
Whatever you pick, write the cadence into the same place as the mode check. A cadence that lives in your calendar and not in the EA's arithmetic is a cadence that will get overruled by a good week.
The First Trading Day After a Payout
This is the session the whole article has been walking toward, because it is the one where every trap fires at once.
The payout has cleared. Equity is lower by the amount withdrawn. If the floor is trailing, it did not move down with the money — so headroom fell by the full withdrawal. The daily-loss counter reset overnight, as it does every session, which makes the account feel like it has a full budget again. It has a full daily budget and a badly reduced total one.
Reset day
The morning after a $6,000 payout on a hypothetical $100,000 account
Headroom above the breach floor4000 / 16000 $
25% of targetA three-day streak needs $16,000 - this is a quarter of it
Daily-loss budget in force2500 / 5000 $
50% of limit usedRecovery mode halves the usual budget
Concurrent positions allowed1 / 1
Limit reachedOne at a time until headroom is rebuilt
Illustrative figures for a trailing floor anchored at the account's $112,000 equity peak.
Nothing about the strategy changed overnight - only the distance to the floor did, and that is the number the EA has to trade against.
Read the first row against the second. The daily budget says the EA may spend $2,500 today. The headroom row says the account only has $4,000 of distance to the floor in total. Two ordinary losing days in a row, entirely inside the daily rules, ends the account. Nothing in the daily-loss guard will stop that, because the daily-loss guard was never asked that question.
So the reset-day posture is not a mood, it is the mode check doing its job:
Recompute the mode before the first bar of the session, not after the first signal. If the peak is stored correctly and the withdrawal has settled, the EA should land in Recovery on its own.
Expect Recovery, and treat Build as a bug. If the EA reports Build the morning after a payout, either the floor is being read from balance instead of equity, or the trailing peak was reset by the withdrawal. Both are worth finding before the first entry.
Hold the reduced size until headroom is rebuilt, not until the day ends. The trigger for returning to full risk is the arithmetic crossing back over the requirement — a date has nothing to do with it.
Keep a manual kill switch within reach for the first session. The account is at its thinnest and the mode logic is running against freshly changed inputs; this is the one session where you want to be able to stop it in a second.
If your firm's payout cycle also resets the window its consistency rule is measured over, that window's first day is now the same day as your thinnest headroom — worth checking, because the two constraints are usually managed separately and they have just landed on top of each other.
Where This Fits With Drawdown Control and the Risk Framework
Everything above assumes three things are already solved, and each belongs somewhere else.
The mode factors multiply a base risk figure — the underlying position-sizing and risk framework decides what that base figure is and how a stop gets placed on a structural level in the first place. This article only changes the multiplier applied to it.
The daily-loss guard is a separate mechanism with a separate trigger; avoiding a daily-loss breach in the funded phase is enforced by an equity kill-switch that fires intraday, while the headroom rule here operates across cycles. They share inputs and solve different problems — and, as the reset-day example showed, the daily guard alone will not catch a total-drawdown problem. If you want the headroom arithmetic checked against your firm's limits directly, the prop-firm drawdown limit calculator does that from the account size and rule set.
And all of it sits downstream of passing a prop firm challenge with an ICT EA — the sequence that gets the account funded in the first place. The rules on this page only start applying the day that sequence ends.
Putting the Rule Set Into Your EA
Five additions, in the order they should go in:
A breach_floor() function that knows whether your firm's anchor is static or trailing, and persists the equity peak across restarts.
A required-headroom constant built from your daily budget, your own worst losing streak plus one, and a measured gap reserve.
A mode check on every bar, before sizing, returning Recovery, Build, or Protect from the headroom arithmetic.
Mode factors applied to all four levers — risk per trade, concurrent positions, correlated exposure, and the daily budget — not to lot size alone.
A withdrawal rule that reads the surplus, requests at a flat moment, and never sizes the request off the balance.
The reason to encode all five rather than run them by hand is not convenience. It is that every one of these decisions is due at exactly the moment you are least objective about it: the week after a good run, or the morning after money landed in your account. A rule written when the account was calm still holds when it is not.
FAQ
Does requesting a payout reset my drawdown limit?
Almost never. A withdrawal reduces your equity; whether it also reduces the breach level depends on how the floor is anchored. Under a static floor the level was fixed at the start and a withdrawal simply moves you closer to it. Under a trailing floor the level was set by your equity peak and stays there, so the headroom you lose equals the amount you took out. Some firms sell a paid reset that re-anchors the floor to your current balance — that is a product, not a default, and it is the only mechanism that genuinely moves the level back.
Can my EA read the breach floor automatically?
It can read every input needed to compute it — equity, balance, and its own stored equity peak — but not the firm's rule. The allowance percentage, the anchor type, and whether the trailing stops at the starting balance are configuration you enter once from the rule text. Get that wrong and the EA will enforce a floor that does not exist, perfectly, all the way to a breach.
Should I stop the EA entirely while a withdrawal is pending?
Only if your firm deducts or ring-fences the amount at request time rather than at processing. If the money is still in the account and still counted, the mode check handles it — the surplus already had the planned request subtracted from it. If the money is deducted immediately, your equity has dropped while your EA still thinks it has not, and pausing new entries until the request settles is the simpler fix.
Is it better to withdraw a fixed percentage or a fixed amount?
Neither, if the figure is chosen in advance. Both are calendar thinking wearing arithmetic clothes — a fixed percentage of a thin account still strips headroom the account cannot spare. Compute the surplus at a flat moment and request no more than that. If you want a predictable income line, take the smaller of your target amount and the surplus, and accept that some cycles pay nothing.
What if my strategy has no long forward test to get a streak number from?
Then you do not have the input, and no formula fixes a missing input. Two honest options: run the strategy forward until a credible worst run exists, or pick a deliberately conservative streak count and treat the resulting buffer as a placeholder that gets replaced by measurement, not as an answer. What you should not do is copy someone else's number — their streak came from their strategy's loss distribution, not yours.
Does this replace the profit target as a trigger entirely?
For risk sizing, yes. The profit target is a firm-side milestone that says a payout is now permitted; it says nothing about whether taking one is safe, because it is measured against your starting balance while your exposure is measured against the floor. Use the target to know when you may request, and the headroom arithmetic to decide whether you should, and how much.
The Funded Desk is the SignalBots editorial team covering prop-firm challenges and funded-account trading. We research and write the guides on evaluation rules, drawdown limits, payout structures and the discipline funded trading demands.

Discussions 0
Leave a comment