Your sweep detector was honest in forex. It marked the previous day's high, waited for price to run it, waited for the reclaim, and fired maybe twice a week. You pointed the same logic at a crypto exchange and now it fires four times a night — and two of those four were nothing at all, just a wick into empty air that never came back.
Nothing is wrong with the pattern. What broke is the reference frame underneath it. Every level your forex logic marks — previous day high, previous day low, session high, session low — borrows its authority from an event: the market stopped, positions settled, and the next bar genuinely began. Crypto never stops. The 00:00 line on your chart is a rendering setting, not a bell, and a level that exists only because a calendar boundary passed has no orders behind it.
This page rebuilds the ICT sweep mechanic in the order your Expert Advisor actually needs it rebuilt: which crypto-native levels replace the ones you lost, how to confirm a sweep is real once "the close" is ambiguous, why a fragmented market puts sweeps in places forex never had them, how to tell an engineered stop hunt from a liquidation cascade, and why the weekend is where forex-trained instincts fail hardest. The broader 24/7 playbook for running ICT across crypto and forex sets up the market-structure framing this assumes; here we take one mechanic and retune it.
Key Takeaways
In crypto a level is valid only if orders actually rest there — equal highs and lows, consolidation extremes and liquidation clusters replace previous-day and session levels.
Two confirmation steps must change: state which timeframe's close counts as the reclaim, and express displacement as a multiple of current volatility, not a fixed distance.
Confirm the sweep against a consensus reference such as the perpetual index price, then execute on your own venue — one exchange's wick is a claim about one book.
A liquidation cascade is not a sweep: collapsing open interest, a perpetual wick deeper than spot, and acceleration through the level mean stand down, not enter.
Table of Contents (25 min read)Contents
What Actually Breaks When There's No Daily Close?
A forex daily close does two separate jobs, and it is worth pulling them apart, because crypto keeps neither.
The first job is settlement. At the rollover, swaps are charged, some desks square up, and a measurable share of the day's positioning is actually resolved. The second job is shared reference. Every participant looking at that instrument sees the same boundary at the same instant, so the high printed before it becomes a level the whole market can point to.
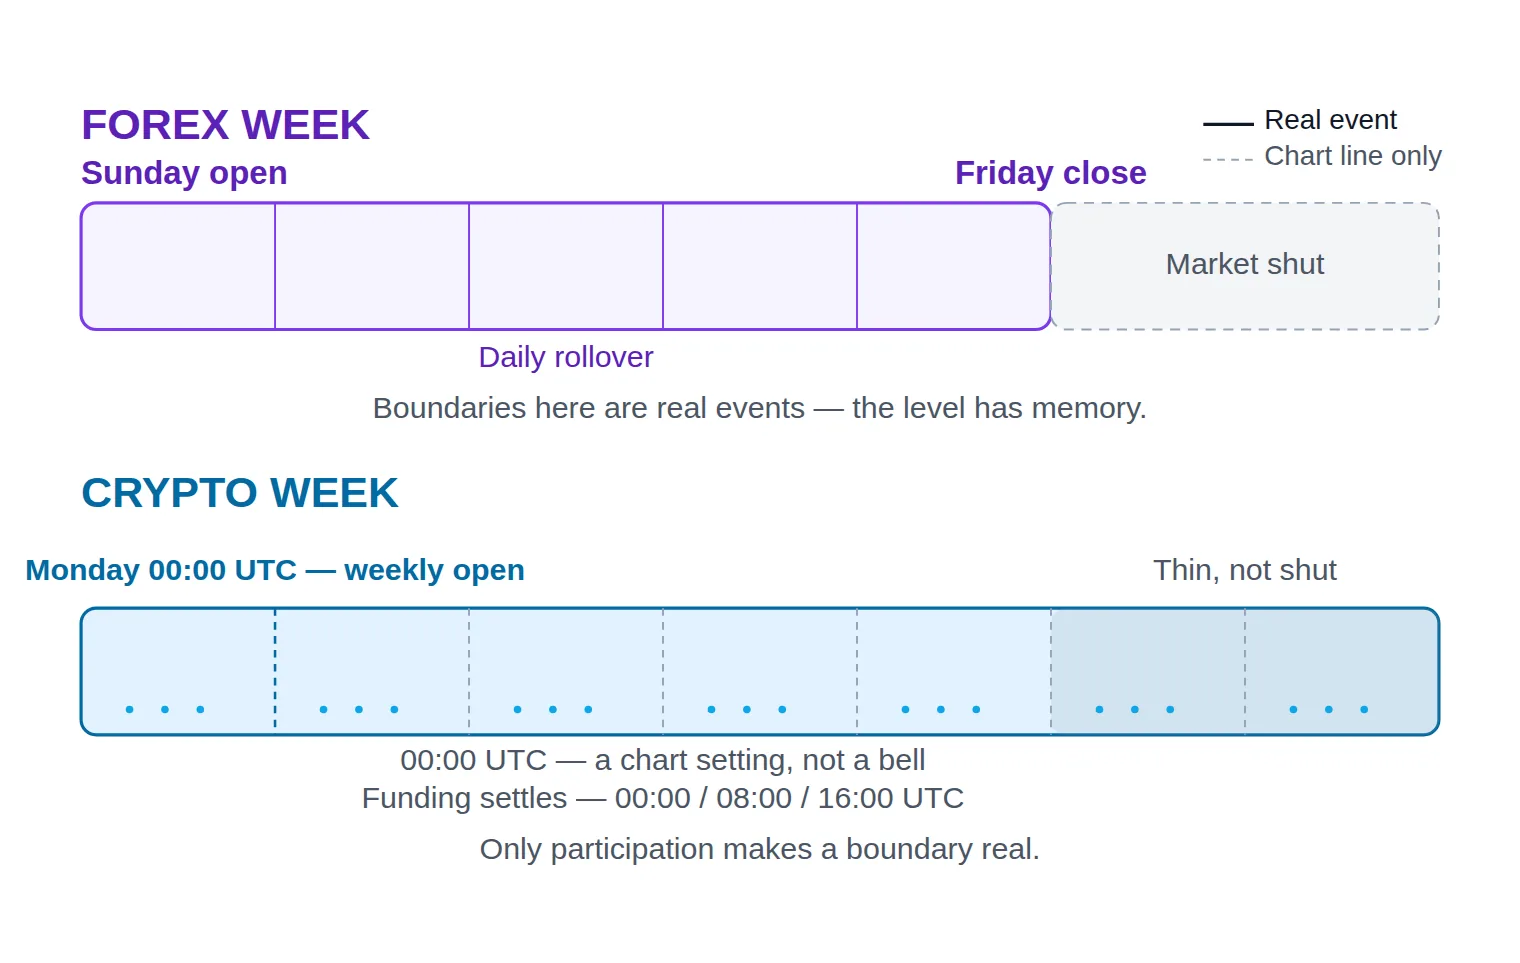
In crypto, neither happens. There is no rollover event on a spot exchange — the matching engine that was running at 23:59 UTC is the same engine running at 00:01. And the boundary is not shared in any meaningful sense either: switch your charting timezone from UTC to New York and "yesterday's high" moves to a different price. The candle is a slice your software drew. Nobody defended it.
That is the whole problem in one line. In forex, the previous day high is a level with memory; in crypto, it is the highest print inside an arbitrary twenty-four-hour window. Sometimes that print happens to coincide with a place where orders rest. Often it does not — and an EA that cannot tell the difference will keep marking levels nobody is standing at.
In forex the week is cut by real events; in crypto the same cuts are lines your chart draws.
So the reframe your logic needs is this: stop deriving levels from the calendar and start deriving them from participation. A level qualifies for crypto liquidity sweeps only if you can answer the question whose orders are sitting there — not what time slice ended here. That question has good answers in crypto, they are just different answers, and the liquidity they describe is real rather than implied.
Crypto is not without shared clocks, either. It has three that the whole venue genuinely agrees on, and the next section maps them onto the forex levels you are giving up. What this page does not do is relitigate whether Smart Money concepts hold up on crypto at all — that verdict is its own argument, and this one assumes you have already made it.
Redefining Liquidity Levels — the Crypto Substitutes for PDH/PDL
Before the mapping, the qualifying rule, because the table is useless without it. In crypto, three things reliably concentrate resting orders:
Equal highs and equal lows — two or more attempts that stalled at nearly the same price. Everyone who faded that level is now holding a stop just beyond it, which is buy-side liquidity above equal highs and sell-side liquidity below equal lows. This is the densest and most reliable pool in the market, and it is entirely independent of what time it printed.
The extremes of a consolidation the whole market watched — a range that held for hours or days accumulates breakout orders on both sides.
Round numbers and visible liquidation clusters on perpetuals — leveraged positions carry a price at which they are closed whether the owner likes it or not, and those prices bunch up.
Notice what is missing: "the level where a candle happened to end." Now the mapping.
Reference-level mapping
Forex reference level
Why it works there
Crypto substitute
What makes the substitute valid
Previous day high / low (PDH/PDL)
The daily close is a real settlement boundary every desk shares
Rolling 24-hour high / low, with the 00:00 UTC daily open as the bias anchor
Only if the extreme already produced a visible reaction — the clock alone confers nothing
Weekly open (Sunday evening)
The entire market reopens at one moment after a two-day pause
Monday 00:00 UTC weekly open
Every major venue and charting default agrees on UTC — pick it once and never mix conventions
Asian / London / New York session high and low
Liquidity providers hand off at fixed hours, leaving each session's extremes behind
Funding-settlement windows on perpetuals (commonly 00:00, 08:00 and 16:00 UTC)
A hard recurring moment when crowded positioning is forced to pay to stay — shared by everyone on the venue
Previous week high / low
The weekend shutdown freezes the level so it stays untested
Consolidation range extremes and equal highs / equal lows
Resting stops are visible in the book rather than implied by the calendar
Friday close and the Monday opening gap
Two days of shutdown create a genuine, unavoidable price gap
No structural equivalent
Even the borrowed reference is gone — CME's crypto futures now trade round the clock, so the weekend futures gap no longer prints
Each forex level survives the jump only if something other than a clock puts orders at that price.
Three of those rows need a sentence of care.
The rolling 24-hour high and low is a magnet, not a trigger. It is a moving window, so the level it reports changes with every new print — code it as a target zone your logic aims at, never as a line a crossing event fires on. What you can fire on is the 00:00 UTC daily open, because it behaves the way a bias anchor should: price trading above it puts the day in premium, below it in discount, and it is the one boundary that essentially every exchange, chart and data feed renders identically.
The funding clock is crypto's session bell. This is the substitution most forex-trained logic misses entirely. On perpetual venues, funding settles on a fixed recurring schedule, and it is a real cost that forces crowded positioning to either pay or unwind. That makes the window before settlement a genuine, shared, repeating moment of pressure — which is exactly the structural job a session handoff did in forex. It is not a level; it is a time your detector should weight, the same way you once weighted the London open.
Anchor your levels to the symbol you will actually execute on. A high printed on BTC/USDT on one venue is not the same number as BTC/USD on another, and an EA that computes levels from one feed and sends orders to another will chase prices that never existed on its own book. Get symbol mapping settled before you tune a single threshold.
One more discipline that costs nothing and prevents a whole class of bug: pick one timezone convention and hard-code it. Mixing UTC candle boundaries with a New-York-midnight bias anchor produces a level set that exists on nobody else's screen — including the screens of the traders whose stops you are trying to locate.
Confirming a Real Sweep: Displacement, Structure Shift, and the Imbalance
The level tells you where. Confirmation tells you whether. This is the part every guide teaches on EUR/USD and nobody retunes for a market that trades continuously with no shared close, so here is the sequence with the crypto adjustments built in.
Confirmation checklist
The five-step confirmation sequence, retuned for crypto
1
Mark a level orders actually rest at
Equal highs, a consolidation extreme, or a level that already caused a visible reaction — never one that exists because a chart boundary passed.
2
Demand a reclaim, not a wick
Price must trade through the level and then close back inside it on your working timeframe. A wick alone is crypto's costliest false positive.
3
Size displacement against live volatility
Measure the impulse as a multiple of recent average range, not in fixed points. A ported forex threshold either never fires or fires constantly.
4
Confirm the structure shift on your feed
The swing that breaks must have existed before the sweep, and it must break on the exact venue and symbol your orders will hit.
5
Enter on the retrace into the imbalance
The displacement candle leaves a gap in price delivery; that gap is the entry zone. Invalidation sits beyond the sweep extreme, not beyond the level.
The sequence is the same one you already know — steps 2 and 3 are where crypto forces a change.
Step 2 is where "no daily close" becomes an engineering decision. In forex you could lean on a daily or 4-hour close and everyone knew what you meant. In crypto you have to state which close you mean, because the only closes that exist are the ones your chart draws. A one-minute close back inside the level is noise; a fifteen-minute or one-hour close is a decision the market had time to make. Write that timeframe into the EA explicitly and treat it as a tuning parameter, not an assumption. The confirmation candle is doing all the work here, so define it.
Step 3 fails silently more often than any other. A displacement threshold expressed in absolute price or points is a forex habit that does not survive contact with crypto, because the same instrument can move quietly for a week and then triple its typical range for a day. Normalise it: require the impulse candle's range to exceed a multiple of recent average true range, and require it to close in the top or bottom third of its own range so a two-sided candle cannot pass as conviction. That single change removes the majority of false signals a ported detector produces, because it makes the rule proportional to current volatility rather than to a number you picked in a different market.
Step 4 is the crypto market structure shift — the break of the swing that was standing before the sweep. Two constraints. The swing must pre-date the sweep, or you are just confirming the sweep against itself. And it must break on your execution venue, for reasons the next section makes uncomfortable.
Step 5 places the risk correctly. The fair value gap left behind after a liquidity sweep is the retrace zone, and it is where the entry belongs — whether those gaps fill at the same rate in crypto as they do in forex is a genuinely separate question with its own answer. Your stop loss goes beyond the extreme of the sweep wick, not beyond the level that was swept; the whole premise of the setup is that the wick was the manipulation, so a stop inside it invalidates you on noise.
Every one of these thresholds is a number you now own and did not own before. Re-run your backtest after each change, on the venue's own data rather than a forex broker's, and expect the tuned values to look nothing like the forex ones.
Why Exchange Fragmentation and Thin Books Move Where a Sweep Fires
Forex has a fragmented dealer market, but your MT5 chart shows one broker's aggregated stream and the majors are deep enough that the differences rarely change what a candle looks like. Crypto has no consolidated tape at all. Your EA reads exactly one book, and the sweep it sees is a claim about that book only.
That produces two failure modes with no forex equivalent.
The venue-local wick. A single large market order on one exchange can walk that book several levels and print a wick that appears on no other venue. Your detector marks it as a sweep of buy-side liquidity; the "reversal" that follows is just the book refilling as market makers requote. There was no engineered stop hunt, and nothing about that print says anything regarding the wider market's intent.
The thin altcoin book. Depth falls away fast outside the largest pairs, and the same notional order travels much further in a shallow book than in a deep one. Wicks stop being events and become routine, so a wick-based detector fires constantly on exactly the instruments where the fills are worst.
Where the wick comes from
ALT/USDTOrder Book
2.4137
PriceSizeTotal
2.5144545
2.4766060
2.4479595
2.4318180180
2.424929502950
2.4203640640
2.4166860860
2.414211801180
2.4137Mid Pricespread
2.413112401240
2.4108910910
2.4072705705
2.4015480480
2.393210210
2.379120120
2.3548080
2.3165555
BidsAsksStatic snapshot · depth = cumulative size
An illustrative mid-cap book: once the block defending 2.4249 is consumed, the next offers sit far above it, so a modest order prints a large wick that looks exactly like displacement.
Read that ladder as your EA would. Everything under 2.4249 looks like a normal market. Above it, the book is nearly empty — so an order that clears the defending block does not "break out with conviction," it simply falls into a hole and gets filled at whatever is left. The candle that results has every visual property of displacement and none of the meaning. This is why depth of market belongs in your instrument filter: if the resting size around a level cannot absorb the flow you are trying to read, wick size is measuring the book's emptiness, not anyone's intent.
The practical fix is two-feed confirmation. Perpetual contracts already solve part of this for you: they are marked against an index price averaged across several spot venues, precisely so that one venue's dislocation cannot trigger liquidations everywhere. Use that index as your consensus reference for whether a level was genuinely swept, and use your own venue's last price for the fill. If the sweep exists on last price but not on the index, it is a venue artefact and your logic should ignore it. That requires a real-time feed for both, which is a small amount of extra plumbing and the highest-leverage filter on this page.
Is That a Liquidity Sweep or a Liquidation Cascade?
Here is the failure mode that produces the worst trades, because the chart pattern is close to identical and the mechanism is the opposite.
An engineered sweep has an author. Someone needs size filled and drives price to where stops rest so their counterparty appears; the reversal is the entire point of the exercise, and everything after the sweep — the displacement, the structure shift, the retrace — is that author working their position. A liquidation cascade has no author. A perpetual venue's risk engine force-closes positions that have breached maintenance margin, each forced close pushes price further, and that push breaches the next tier of positions. It is a feedback loop, not a plan. Nobody involved wants price back at the level.
Liquidation cascade vs engineered liquidity sweep
Liquidation cascade
Forced closes — the venue's risk engine is sending the orders, not a participant
Accelerates through levels instead of stopping at one
Open interest collapses: positions are leaving, not being built
The perpetual prints a deeper wick than spot and the index price
Funding flips hard as the crowded side is wiped out
A liquidity event with no author — treat it as risk to survive, not a setup to trade.
VS
Engineered sweep
Deliberate — price is driven to a level where stops are known to rest
Stops at the level, reclaims it, then reverses with intent
Open interest builds on the reversal side as new positions load
Spot, perpetual and index agree: the wick is roughly the same on all three
Leaves a clean imbalance that the retrace comes back to fill
The pattern your checklist was written for — confirmable first, tradable second.
Same silhouette on the chart, opposite mechanism underneath — and only one of them has a counterparty who wants price back.
Four of those tells are machine-readable, which means your EA can use them rather than you eyeballing them after the fact:
Open interest direction across the move. Positions closing en masse and positions being opened are opposite signatures, and the venue publishes the number.
Perpetual-versus-index wick divergence. A cascade is a derivatives event; it tears the contract away from the spot index it is marked against. An engineered sweep in spot shows up on both.
Behaviour at the level. A sweep decelerates into the level, takes what is there, and turns. A cascade accelerates through it and keeps going, because each fill creates the next seller.
Recovery shape. Cascades snap back in a sharp V that retraces much of the move without leaving a structured displacement-and-imbalance sequence behind. If there is nothing to retrace into, there was nothing engineered.
Two operational consequences. First, expect brutal slippage during a cascade — the whole reason the loop runs is that resting orders are being consumed faster than they are replaced, so a market order sent into it fills nowhere near the price your logic saw. Second, give the EA a post-cascade cooldown: a fixed window after a detected cascade during which sweep entries are suppressed entirely, backed by a hard kill switch on the daily loss it can absorb.
If you want to see where the liquidation clusters that feed these loops actually sit for a position at a given leverage, run the numbers on our crypto liquidation price calculator — the prices it returns are the prices the risk engine acts on, and they cluster around exactly the round numbers your level logic is already watching.
If "no daily close" is the theme, the weekend is its loudest expression. Forex shuts on Friday evening and does not reopen until Sunday evening. Crypto does not shut, and a forex-trained instinct — nothing happens over the weekend, wait for Monday — is not merely unhelpful here, it is inverted.
What actually changes is who is quoting. Many of the desks and market makers that provide depth in crypto also run books in other asset classes, and a meaningful share of that inventory steps back when the traditional week ends. Depth thins across the board. The mechanical consequence follows directly from the ladder above: when the book is thinner, the same order size moves price further. A weekend sweep costs whoever prints it a fraction of what a Tuesday-afternoon sweep would cost.
Two things follow for your logic.
More sweeps fire, and a larger share of them fail. Cheap manipulation is common manipulation. Levels get run over the weekend that would have held on a weekday, and plenty of those runs never produce the displacement and structure shift that make them tradable — they were just a thin book being pushed.
The weekend range becomes Monday's target. Because so little real positioning is established over the weekend, the extremes it prints sit there as untested, obvious liquidity. It is routine for the first hours of the trading week to run the weekend high or the weekend low before the week's actual move gets going — which is precisely why the Monday 00:00 UTC weekly open earns its place in the level table.
There is also a reference point that recently disappeared. For years, crypto traders treated the weekend gap on CME's bitcoin futures chart as a magnet, because those contracts closed while spot kept trading. Since CME moved its crypto futures to round-the-clock trading, that gap no longer forms. If your chart shows a weekend price gap today, treat it as a venue artefact — a maintenance window, a feed restart, a data outage — and not as a structural level anyone is trading toward.
The practical answer is a regime, not a rule: use a trading session filter that recognises the weekend as its own state, and inside that state raise the confirmation bar rather than switching off blindly. A larger displacement multiple, a higher-timeframe reclaim, mandatory index confirmation, reduced size — any of those keep you in the market for the genuine weekend sweeps while discarding the thin-book noise. Killzone-style session windows are a forex mechanic and do not translate here; the weekend regime is the crypto equivalent of session awareness.
Here is the whole sequence on one illustrative weekend chart.
Worked example
Illustrative weekend sweep and reversal on BTC/USDTBTC/USDT1H
Illustrative, not a record of a real session: the shaded band is the imbalance the displacement leaves behind, and the entry sits inside it with invalidation above the sweep wick.
Walk it in the order your EA would evaluate it. Two attempts stall within a few dollars of 61,850, which qualifies the level — those are matched highs with stops resting above them, not a calendar artefact. Price then trades to 62,230, well through the level, and the hourly candle closes back at 61,810, inside the range: that is the reclaim, and the wick alone would not have been enough. The next candle drops through 61,240, the low that was standing before the sweep, which is the structure shift. It leaves an imbalance roughly between 61,560 and 61,760, price retraces into it, and the entry fills at 61,650 with the stop at 62,260 — above the sweep extreme, not above the level. Risking 610 to make 1,220 is a reward-to-risk ratio of two to one on this hypothetical, which is the arithmetic the setup exists to produce, not a promise about how often it works.
Watching the Checklist Run on a Live Crypto Feed
A checklist you cannot see running is hard to trust and harder to tune. The thresholds this page hands you — which reclaim timeframe, what displacement multiple, how much index divergence to tolerate — are not values anyone can hand you correctly in the abstract. You calibrate them by watching confirmed sequences form and comparing them to what your own detector said at the same moment.
That is the honest use for our live crypto signals feed: it surfaces sweep-and-reversal setups on live crypto charts as the displacement and imbalance confirmation forms, so you have a second opinion arriving in real time while you tune. Open one alongside your own chart and interrogate it against the five steps. Does the flagged level correspond to equal highs or a consolidation extreme, or only to a time boundary? Did the reclaim close on a timeframe you would actually trade? Is there a visible imbalance the retrace can work into, and where would invalidation sit relative to the sweep wick? Disagreements are the useful part — every one of them points at a threshold in your own logic that is set too tight or too loose.
Be clear about what it is and is not. It is a feed of already-identified setups, not a rule engine you configure. If what you want is your own sweep-detection logic running as code, on your own levels and your own thresholds, against your own exchange account, that is the EA and connector path and the feed will not substitute for it. And no feed, ours included — please read our risk warning — changes the fact that a confirmed sweep is a probability, not an outcome.
Key Takeaways
Back to the four alerts a night. Two of them were nothing because two of them were marked against levels no one was standing at — a slice boundary your charting software drew, not a place where orders rest. Fixing crypto liquidity sweeps is not a matter of adding filters on top of forex logic; it is a matter of replacing the reference frame underneath it and then retuning every threshold that was calibrated in a market with a bell.
Levels come from participation, not the calendar. Equal highs and lows, consolidation extremes, and liquidation clusters replace PDH/PDL. The 00:00 UTC open is your bias anchor, Monday 00:00 UTC is your weekly reset, and the funding clock is the closest thing crypto has to a session bell.
Two steps of the confirmation sequence must change: define which timeframe's close counts as the reclaim, and express displacement as a multiple of current volatility instead of a fixed distance.
Confirm the sweep on a consensus reference, execute on your own venue. One exchange's wick is a claim about one book; the perpetual index price is the closest thing to a market-wide second opinion.
A cascade is not a sweep. Collapsing open interest, a perpetual wick deeper than spot, and acceleration through the level instead of rejection at it mean the risk engine is trading, not a counterparty — suppress entries and wait.
FAQ
Does previous day high/low work at all in crypto?
Sometimes, but not for the reason it works in forex. A rolling 24-hour extreme occasionally lands on a price where orders genuinely rest — usually because it coincides with equal highs or a range boundary that formed independently. When it does, it is a valid level, and the twenty-four-hour framing is incidental. When it does not, it is just the largest number inside an arbitrary window. The safe implementation is to compute the level from structure first and only then check whether it happens to sit near the 24-hour extreme, rather than the other way round.
Which timezone should my EA use for crypto candles?
UTC, and only UTC, throughout the entire system. The specific choice matters less than the consistency, but UTC is what almost every exchange API, charting default and data provider uses, which means your levels line up with the levels other participants can see. The failure to avoid is mixing conventions — computing candles in UTC while anchoring bias to a New-York-midnight open produces a hybrid level set that exists nowhere except in your code.
How do I stop my EA firing on every wick?
Two changes handle most of it. Require a close back inside the level on a meaningful working timeframe rather than accepting the wick as the event, and express your displacement threshold as a multiple of recent average range instead of a fixed price distance. Add a depth filter so the instrument's book can absorb the size you intend to trade, and the remaining false positives are mostly venue-local wicks — which two-feed confirmation against the perpetual index price will catch.
Can a liquidity sweep and a liquidation cascade happen at the same time?
Yes, and that is the genuinely difficult case. A sweep can push price into a dense cluster of liquidation prices and set off a cascade that carries far beyond what the original move intended. The practical handling is not to classify it but to stand down: when open interest is collapsing and the perpetual has torn away from its index, the fill quality is bad enough that even a correctly identified setup is not worth taking. Wait for the contract and the index to converge again and for a fresh structure to form.
Should my EA trade crypto sweeps over the weekend?
Only under a different set of thresholds. The weekend is not dead time in crypto, but it is thin time, and thin books make sweeps cheap to manufacture and less likely to follow through. Treat the weekend as its own regime in your session filter: raise the displacement multiple, require the reclaim on a higher timeframe, insist on index confirmation, and reduce size. Switching off entirely is a defensible choice too — what is not defensible is running weekday thresholds unchanged.
Do session highs and lows mean anything in crypto?
Weakly, and for a borrowed reason. Crypto participants overlap with traditional markets, so activity does pick up around the London and New York hours and the extremes printed in those windows sometimes hold. But that is correlation with another market's schedule, not a structural property of a venue that never closes. The crypto-native equivalent — a recurring, venue-wide moment that forces positioning to reprice — is the funding settlement window, and it is the one your detector should weight.
Sources & Further Reading
Want to go deeper? These independent, authoritative sources shaped this guide — each one is worth reading in full:
The Crypto Desk is the SignalBots editorial team behind our digital-asset coverage. We research and write the guides and explainers on spot and perpetuals, exchange mechanics, funding rates and the 24/7 structure that sets crypto apart from every other market.

Discussions 0
Leave a comment